
Blogs
PW Consulting: Nitrogen Gas Springs Market to Grow 5.7% CAGR, Reaching $657.3M by 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence in a Pressurized Market: The 2026 Nitrogen Gas Springs Industry Outlook
The industrial tooling landscape is undergoing a period of significant recalibration. As manufacturers navigate post-pandemic supply chain realities, shifting regulatory frameworks, and the relentless push toward Industry 4.0 integration, the nitrogen gas spring market has emerged as a critical focal point for operational efficiency and capital allocation. At PW Consulting, we recognize that understanding this market requires more than surface-level trend tracking. It demands a granular, forward-looking analysis that translates macroeconomic signals into actionable strategic directives.
Nitrogen Gas Springs Market
Our latest comprehensive market research publication, launched to support enterprise decision-making throughout 2026 and beyond, delivers precisely that capability. This article serves as a strategic primer, outlining the analytical architecture, competitive intelligence framework, and operational dynamics that define the study. We will examine why this research represents a critical asset for procurement leaders, strategic planners, and market expansion teams operating in the precision tooling sector. For executives who require the complete quantitative matrices, regional breakdowns, and deep-scenario modeling, the full report is available for immediate access through our research portal.
The Grand Trajectory: Mapping the 2026–2032 Forecast Horizon
The nitrogen gas springs market has demonstrated remarkable resilience and structural growth over the past half-decade. Drawing upon a rigorous historical dataset spanning 2020 through 2025, our analysis captures the full arc of market evolution—from the contraction pressures observed in 2021, through the steady recovery and expansion that defined the mid-to-late 2020s. By the close of the base year, the market had firmly established a momentum baseline that positions it for sustained appreciation across the forecast horizon.
Our forward-looking projections extend through 2032, charting a clear upward trajectory that underscores the sector's fundamental attractiveness. The compound annual growth rate anchored at 5.7 percent reflects a mature yet dynamically expanding ecosystem, driven by incremental adoption in precision stamping, injection molding, and advanced industrial machinery. Importantly, this growth narrative is not merely a linear extrapolation. It is the product of layered scenario modeling that accounts for technological adoption curves, capital expenditure cycles in end-user industries, and the gradual normalization of raw material supply chains.
Revenue figures, denominated in USD millions, illustrate a market that has consistently scaled beyond the 400 million threshold in recent years and is positioned to surpass critical psychological and operational milestones in the coming years. The projection curve reveals acceleration points that coincide with broader industrial modernization waves, particularly in regions where automation investment is reaching inflection. For strategic planners, these trajectory markers provide essential baseline parameters for capacity planning, supplier negotiations, and long-term inventory strategy. The complete temporal decomposition, including year-by-year variance intervals and sensitivity ranges, is fully detailed within the report's forecasting modules.
Architecture of the Analysis: What the Report Delivers
PW Consulting's market study is structured to function as an operational decision-support system rather than a static reference document. Every section has been engineered to address the concrete questions that arise during quarterly strategic reviews, M&A screening, and portfolio optimization exercises. The report's architecture encompasses several core pillars designed to give readers immediate tactical utility.
Granular Segment Mapping and Cross-Functional Overlay
The analysis disaggregates the market across multiple structural dimensions, allowing stakeholders to isolate performance drivers and identify high-yield opportunity corridors. Type-based segmentation traces the evolution of standard, compact, super compact, and micro nitrogen gas spring categories, examining how force ranges, footprint constraints, and application specificity are reshaping purchasing criteria. Application-level analysis evaluates demand concentration across automotive, aerospace, industrial machinery, and specialty sectors, highlighting where production volume aligns with margin expansion potential.
Regional demand architecture is similarly decomposed, mapping consumption intensity, growth velocity, and supply chain proximity across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. By avoiding simplistic aggregation, the report enables readers to assess regional attractiveness through a multi-factor lens that weighs industrial base maturity, regulatory exposure, logistics complexity, and competitive saturation. All quantitative splits, share distributions, and absolute valuation figures for each segment and sub-segment are exclusively available in the full data appendix.
Gas Spring Market
Competitive Intelligence and Strategic Positioning Frameworks
The competitive landscape section moves beyond roster enumeration to deliver actionable profiling of the market's leading participants. Each profiled enterprise is evaluated across capability depth, geographic footprint, product architecture, innovation cadence, and commercial positioning. The analysis situates players within a broader competitive topology, identifying where scale advantages, technological differentiation, or distribution reach create defensible market positions.
Among the organizations subjected to this detailed scrutiny are DADCO Inc., Special Springs s.r.l., Hyson Products Inc., Pascal Engineering Corporation, KALLER, Bordignon S.r.l., Isotech Inc., Gemini Gas Springs Inc., AZOLGAS, and FIBRO GmbH. The report examines how each entity constructs its value proposition, responds to segment-specific demands, and navigates the tension between standardized catalog offerings and custom engineering engagements. For readers evaluating partnership opportunities, benchmarking their own positioning, or assessing acquisition targets, this competitive mapping provides an essential reference framework. The full profile set, complete with capability matrices and strategic assessment summaries, is contained in the proprietary competitive intelligence section of the report.
Competitive Landscape and Innovation Vectors
The nitrogen gas springs market is characterized by a moderately concentrated structure, with the top three participants collectively commanding a significant share of total revenue and the top five firms consolidating an even larger portion of industry output. This concentration pattern reflects the capital intensity of manufacturing, the importance of certification compliance, and the value that end-users place on supply reliability and technical support. At the same time, the presence of specialized domestic producers and niche innovators ensures that competitive pressure remains dynamic across both premium and cost-sensitive segments.
Innovation in this market is increasingly oriented toward digitalization, safety enhancement, and environmental resilience. DADCO Inc. garnered attention in early 2025 with the introduction of an IoT-enabled nitrogen gas spring series featuring integrated pressure and temperature monitoring, explicitly designed to support Industry 4.0 die tooling architectures. This move signals a broader industry shift where gas springs are no longer viewed merely as passive mechanical components but as intelligent nodes within connected manufacturing systems. The ability to monitor performance in real time, predict maintenance intervals, and optimize press cycles represents a tangible value-add that forward-looking OEMs are beginning to mandate.
On the safety and durability frontier, Special Springs s.r.l. advanced its product portfolio through multiple strategic updates throughout 2025. The launch of the Skudo-Flex accessory addressed cylinder longevity and operational safety in heavy-duty stamping environments, while the subsequent release of a new US Series catalog and an enhanced reducer component expanded the firm's capacity to perform in contaminated operating conditions. The company also rolled out a Fair Kit initiative to strengthen its trade exhibition presence, reinforcing its commitment to direct market engagement and customer education. These initiatives illustrate how sustained R&D investment, catalog expansion, and targeted commercial activation converge to build competitive moats.
Other market participants continue to differentiate through complementary vectors. Hyson Products Inc. maintains a full-line approach encompassing high-force configurations, slow-return variants, and contamination-resistant models tailored to metal stamping dies and injection molds. Pascal Engineering Corporation emphasizes precision and safety in mini and standard gas springs for stamping and molding applications, serving manufacturers who prioritize component quality as a productivity multiplier. KALLER has carved out a distinct position with high-temperature variants engineered to withstand operating conditions up to 250°C, addressing the demands of hot stamping processes. Bordignon S.r.l. leverages decades of heritage—dating back to 1958—to compete on longevity, reliability, and incremental innovation in stamping and forming applications. Isotech Inc. and Gemini Gas Springs Inc. extend the competitive field with steel and stainless steel offerings and in-house manufactured lift supports that meet stringent industrial standards, respectively. Meanwhile, AZOLGAS provides extensive catalog breadth for metal stamping and multi-technology industrial use, and FIBRO GmbH supports time-sensitive procurement with an expansive standard catalog and central European warehousing that enables same-day delivery.
Together, these players illustrate a market where competitive advantage is derived from a blend of engineering rigor, application-specific customization, digital readiness, and supply chain responsiveness. For enterprises evaluating supplier selection or attempting to anticipate competitor moves, the report's competitive analysis section decodes these positioning strategies in detail.
Structural Dynamics and the Operating Environment
No market analysis is complete without a rigorous examination of the external forces that shape supply, demand, and compliance risk. The nitrogen gas springs sector operates within a regulatory and materials environment that directly influences product specifications, production economics, and market access.
Regulatory Architecture and Standards Compliance
The standards landscape for nitrogen gas springs is defined by a cohesive set of international and regional requirements that establish baseline expectations for safety, performance, and interchangeability. ISO 11901-5:2021 specifies that nitrogen is the exclusive gas permitted for charging gas springs in stamping die applications, mandating commercial-grade nitrogen in purity class 5.0. This standard, alongside the broader ISO 11901 framework governing dimensions, forces, and safety instructions for press tools and dies, creates a harmonized technical baseline that manufacturers must satisfy to operate in global markets.
In the European context, compliance with the Pressure Equipment Directive (PED 2014/68/EU) remains mandatory for nitrogen gas springs deployed in machinery and tooling applications. Additionally, mounting dimensions and interchangeability specifications are shaped by VDI 3003 and CNOMO standards, which define mechanical interfaces critical to industrial stamping operations. These regulatory and standards-driven requirements function as both a barrier to entry and a quality signal, reinforcing the market position of firms that have invested in certified production processes and comprehensive documentation capabilities. The report's dynamics section examines how compliance costs, certification timelines, and standards evolution influence competitive accessibility and regional market entry strategies.
Raw Material Volatility and Cost Transmission
The economics of nitrogen gas spring manufacturing are materially influenced by steel price dynamics. Supply chain disruptions, geopolitical tensions, and demand-side fluctuations continue to inject volatility into raw material markets, with direct consequences for production costs and margin stability. Firms that maintain diversified sourcing strategies, forward-contracting arrangements, or value-engineered material specifications are better positioned to absorb cost shocks without eroding competitiveness. The analysis explores how cost transmission mechanisms vary across product categories and customer segments, and how procurement strategy can be aligned with broader market timing to optimize input cost exposure. Detailed cost-structure benchmarks, sensitivity coefficients, and sourcing scenario evaluations are provided in the full report's operational economics modules.
Strategic Implications for 2026 Decision-Makers
Translating market intelligence into executable strategy requires connecting high-level trends to organizational capabilities and constraints. For executives operating in or adjacent to the nitrogen gas springs market, several strategic imperatives emerge from the evidence base assembled in this study.
First, the growth trajectory and segment dynamics suggest that disciplined portfolio allocation will outperform undifferentiated expansion. Firms that map their product and service offerings to the application and type segments demonstrating the strongest alignment between demand growth, margin potential, and competitive accessibility will be best positioned to capture disproportionate value. The report's segment-level decomposition provides the diagnostic foundation for such allocation decisions.
Second, the competitive landscape analysis underscores the enduring importance of differentiation in a moderately concentrated market. While scale and distribution provide baseline advantages, sustained leadership increasingly depends on targeted innovation, whether in digital monitoring capabilities, high-temperature performance, contamination resistance, or rapid fulfillment infrastructure. Companies that treat product architecture as a strategic variable rather than a static attribute will uncover opportunities to premiumize their offerings and deepen customer lock-in.
Third, regulatory and materials dynamics introduce both risk and opportunity. Companies that proactively align their engineering and compliance functions with the evolving standards environment reduce the likelihood of market access disruptions and position themselves as trusted partners to risk-averse end-users. Simultaneously, effective raw material management—through supplier diversification, inventory optimization, and design-for-cost initiatives—can transform input volatility from a margin threat into a competitive differentiator.
Finally, the industry's movement toward connected, intelligent tooling components signals that the definition of value in this market is expanding. The integration of monitoring, data capture, and predictive capabilities into nitrogen gas spring products reflects a broader shift in which suppliers are expected to contribute to their customers' operational intelligence. Organizations that anticipate this shift and invest accordingly will be better positioned to capture the next wave of demand growth.
Accessing the Full Intelligence Package
This article has outlined the scope, methodology, and strategic relevance of PW Consulting's Nitrogen Gas Springs Market research, highlighting the structural trends, competitive dynamics, and operational considerations that will shape decision-making throughout 2026 and into the 2032 forecast horizon. The narrative presented here is intentionally high-level, designed to demonstrate the analytical rigor and practical applicability of the study while preserving the proprietary depth that delivers maximum value to our clients.
The complete report contains exhaustive year-by-year market sizing, detailed segment splits, regional revenue distributions, competitive capability matrices, scenario-based forecasts, and operational benchmarking data. Every quantitative insight referenced in this overview, along with granular sub-segment performance indicators and strategic recommendation frameworks, is fully documented within the publication. For procurement executives, strategy directors, market analysts, and investment professionals who require the full evidentiary base to support capital allocation, supplier negotiation, and market entry decisions, the complete report is available for immediate access. We invite you to consult the full intelligence package to ensure your 2026 planning is grounded in the most comprehensive and strategically actionable market analysis available.
For detailed analysis of this topic, please visit the official page: Nitrogen Gas Springs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Educational Toys Market to Hit $48.23 Billion by 2032, 8.47% CAGR
By pmarketresearch, 2026-09-15
The Educational Toys Market: Strategic Intelligence for 2026 and Beyond
The landscape of childhood development is undergoing a profound transformation, driven by shifting pedagogical priorities, technological integration, and an increasing recognition of play as a fundamental vehicle for learning. For executives navigating the consumer goods and education sectors, the Educational Toys Market represents not merely a niche segment but a critical battleground for future growth. As we move through 2026, the decisions made today regarding product portfolios, supply chain resilience, and compliance frameworks will determine market leadership over the next decade.
PW Consulting is pleased to present our comprehensive market research report on the Educational Toys Market, designed to equip stakeholders with the actionable intelligence required to capitalize on emerging opportunities. This analysis provides a rigorous examination of market trajectories, competitive pressures, and regulatory shifts that define the current operating environment from 2026 through 2032.
Market Trajectory and Macro Dynamics
Understanding the broader economic footprint of the Educational Toys Market is the first step in strategic planning. Historical analysis reveals a sector characterized by steady, resilient expansion. Between 2020 and 2025, the market exhibited robust growth, with revenue climbing from 19.2 Billion USD to 27.24 Billion USD. This trajectory underscores the increasing willingness of parents, educators, and institutions to invest in products that blend entertainment with developmental outcomes.
Looking forward, the forecast period from 2026 to 2032 projects continued upward momentum. The market is expected to reach 29.13 Billion USD in 2026, accelerating towards 48.23 Billion USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 8.47%, signaling a healthy expansion phase that outpaces many traditional consumer discretionary categories. For strategic planners, this indicates sustained demand elasticity, provided that products align with evolving consumer expectations regarding safety, educational efficacy, and digital integration.
However, raw growth figures only tell part of the story. The structure of this growth is fragmented across diverse product types, application scenarios, and geographical regions. While aggregate numbers suggest optimism, the distribution of value across these segments reveals distinct strategic priorities. Certain application areas are already demonstrating higher revenue concentrations, suggesting where consumer spending is most heavily directed, while regional variances highlight differences in market maturity and regulatory environments. Identifying which specific categories are driving the bulk of this expansion requires a granular analysis that goes beyond top-line estimates.
Report Scope and Operational Utility
Our report is structured to move beyond theoretical market sizing and provide practical tools for business decision-making. The analysis covers a historical window from 2020 to 2025 to establish baseline trends, followed by a forecast period extending to 2032. This longitudinal view allows organizations to distinguish between temporary pandemic-era anomalies and structural shifts in purchasing behavior.
The research encompasses a detailed segmentation analysis across three primary dimensions: product types, application contexts, and regional markets. By dissecting the market along these axes, we enable clients to identify high-potential niches that may be obscured in aggregate data. The report examines the specific revenue contributions of categories ranging from motor skills and arts and crafts to STEM-focused products and role-play instruments. Similarly, the application landscape is analyzed to distinguish between early childhood development needs, formal school curriculum integration, and other usage scenarios. Regional breakdowns further clarify where growth is most pronounced, allowing for targeted geographic expansion strategies.
A critical component of this research is the evaluation of market concentration. Current metrics indicate that the top three players hold a 30.0% share of the market, while the top five control 40.0%. This level of concentration suggests a moderately consolidated landscape where dominant incumbents wield significant influence over pricing, distribution, and brand perception. However, the remaining market share is distributed among a diverse array of specialists and innovators, creating opportunities for agile entrants who can differentiate through niche expertise or technological innovation.
To ensure the highest level of strategic utility, the report incorporates profiles of key market participants. These profiles examine the specific educational offerings, product portfolios, and strategic positioning of leading companies. By understanding the strengths and focus areas of competitors such as major construction toy specialists, interactive electronics manufacturers, and STEM curriculum providers, organizations can better anticipate competitive moves and identify gaps in the market.
Educational Toys Market
Competitive Landscape: Incumbents and Innovators
The competitive dynamics of the Educational Toys Market are shaped by a mix of legacy toy giants and specialized educational technology firms. Each player brings a distinct value proposition, ranging from mass-market brand recognition to targeted pedagogical solutions.
Among the established leaders, companies like Mattel, Inc. and The LEGO Group maintain strong positions by leveraging iconic brands and extensive distribution networks. Mattel offers a wide range of educational toys including construction sets, STEM learning products, and interactive play items. The LEGO Group, including its dedicated LEGO Education division, specializes in construction-based educational toys and STEM sets designed for scientific discovery and creativity. Notably, in January 2026, LEGO Education launched new STEM sets for children aged 7 and above designed to inspire curiosity, exploration, and scientific discovery, signaling a continued commitment to the older end of the youth demographic. Ravensburger AG also contributes to this competitive sphere, offering wooden puzzles, board games, and STEM building sets for cognitive development.
Hasbro, Inc. rounds out the major incumbent group with a focus on educational games, role-playing sets, and STEM-oriented toys for skill development. These large-scale players benefit from economies of scale and brand loyalty, but they also face pressure to innovate rapidly in response to technology-driven competitors.
On the electronics and interactive learning side, VTech Holdings Ltd. and LeapFrog Enterprises, Inc. are pivotal. VTech manufactures electronic learning toys, interactive tablets, and educational software for early childhood development. LeapFrog develops interactive electronic learning toys and books that combine technology with early education. In May 2025, LeapFrog showcased its latest collection of educational toys, including the Strum & Count Wooden Guitar, at Toy Fair 2025, highlighting a strategy that blends traditional tactile play with musical and cognitive learning. JAKKS Pacific, Inc. further complements this segment by manufacturing educational electronic toys and interactive STEM products.
The market is also seeing significant activity from specialized innovators. Osmo, Inc. offers interactive tablet-based educational games and learning kits for ages 3-11, bridging the gap between physical manipulatives and digital interfaces. MindWare, Inc. focuses on hands-on learning tools and manipulatives for science, math, and critical thinking, appealing to parents and educators seeking rigorous cognitive development tools. Spin Master Corp. provides STEM and interactive educational toys, including licensed educational lines, while Melissa & Doug, LLC specializes in wooden educational toys, puzzles, and open-ended play sets for preschoolers, catering to the demand for screen-free, age-appropriate products. Tomy Company, Ltd. from Japan develops educational construction toys, robotics, and STEM learning products, adding a strong international dimension to the competitive field.
Recent developments underscore the pace of innovation and the need for vigilance. In October 2025, STEMPlay Labs launched Wonder Briks and PictoMath, patent-pending construction bricks and math tools for STEM play, demonstrating how new entrants are targeting specific learning outcomes with proprietary technology. More recently, in May 2026, Smart Kids Planet expanded its age-specific STEM and educational toy lines for children ages 1-13 to align with modern developmental needs, reflecting a trend toward granular age segmentation. Conversely, regulatory scrutiny remains high. In March 2026, ZMC Group recalled multiple light-up toys due to battery ingestion hazards violating toy safety standards, a reminder of the operational risks associated with product safety compliance.
Regulatory Dynamics and Compliance Imperatives
For strategic planners, the regulatory environment is as critical as market demand. The Educational Toys Market is subject to stringent safety and quality standards that vary significantly across jurisdictions and are currently undergoing substantial updates.
In the United States, the Consumer Product Safety Commission (CPSC) has taken decisive action. On December 12, 2025, the CPSC published its final rule on Safety Standard for Toys: Requirements for Water Beads. This rule takes effect on March 12, 2026, and holds particular significance because it codifies requirements directly into 16 CFR Part 1250 rather than updating ASTM F963. This structural change implies a more rigid regulatory framework that manufacturers must integrate into their compliance systems immediately.
Across the Atlantic, the European Union has introduced the new Toy Safety Regulation 2025/2509, published on December 12, 2025. This regulation enters into force on January 1, 2026, and will apply fully on August 1, 2030. A standout feature of this regulation is the introduction of a digital product passport requirement for all toys, enhancing traceability and compliance. For companies operating in or exporting to the European market, this necessitates investment in digital infrastructure and supply chain transparency that goes beyond traditional labeling requirements. Failure to adapt to these requirements could result in significant market access barriers and reputational damage.
Educational Furniture Market
These regulatory shifts are not isolated events; they are part of a broader trend toward heightened consumer protection and ingredient transparency. Organizations must factor compliance costs, lead times, and potential reformulation needs into their product roadmaps. The interaction between rapid product innovation and rigorous safety testing creates a strategic tension that must be managed carefully to avoid recalls or market exclusion.
Strategic Imperatives for 2026 and Beyond
As the Educational Toys Market progresses through 2026, several strategic imperatives emerge for market participants. First, the divergence in growth rates across product types and applications demands a nuanced portfolio strategy. Companies cannot rely on a one-size-fits-all approach; instead, they must align product development with the specific developmental needs and purchasing behaviors of their target segments. Whether focusing on early childhood development, school curriculum integration, or other applications, the value proposition must be clearly articulated and substantiated.
Second, the competitive landscape requires continuous vigilance. The presence of both massive incumbents and agile innovators means that market share can shift quickly. Monitoring the product launches, patent activities, and strategic expansions of key players is essential for anticipating competitive pressure. The recent launch activities by LEGO Education, STEMPlay Labs, and Smart Kids Planet illustrate the diversity of innovation happening in real time, from new STEM sets for older children to patent-pending construction tools and expanded age-specific lines.
Third, regulatory compliance must be treated as a strategic capability rather than a back-office function. With the U.S. water beads rule already in effect and the EU digital product passport requirement looming, companies that proactively embed compliance into their design and manufacturing processes will gain a competitive advantage. This is particularly relevant for products involving electronics, small parts, or novel materials, where safety risks are heightened.
Finally, geographic strategy must account for regional differences in market maturity, consumer preferences, and regulatory frameworks. While some regions currently represent larger revenue pools, others may offer higher growth potential or less saturated competitive environments. Understanding the specific dynamics of North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa is crucial for optimizing market entry and expansion efforts.
Conclusion
The Educational Toys Market stands at a pivotal juncture, characterized by robust growth, intense competition, and evolving regulatory demands. The data indicates a market expanding from 27.24 Billion USD in 2025 to a projected 48.23 Billion USD by 2032, driven by a CAGR of 8.47%. However, realizing value in this environment requires more than awareness of these aggregate figures; it demands deep segmentation analysis, competitor intelligence, and a proactive approach to compliance.
PW Consulting's full market research report provides the detailed segmentation splits, regional revenue breakdowns, and granular application-level data necessary to construct a precise strategic roadmap. By accessing the complete report, organizations can uncover the specific growth velocities of individual product categories, identify the exact revenue contributions of each region, and benchmark their positioning against the detailed profiles of market leaders. We invite you to explore the full intelligence suite to ensure your 2026 decisions are grounded in comprehensive, actionable insight.
For detailed analysis of this topic, please visit the official page: Educational Toys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Prefab Bathroom Pods Market to Hit $12.59 Billion by 2032, CAGR 9.4%
By pmarketresearch, 2026-09-15
Strategic Intelligence for a Modular Future: Inside the Prefabricated Bathroom Pods Market Research 2026
The construction industry is rapidly shifting toward offsite manufacturing, and the bathroom pod segment stands at the center of this transformation. Over the past half-decade, the global market for prefabricated bathroom pods has evolved from a niche acceleration tool into a mainstream procurement strategy for developers, contractors, and facility owners. Our latest market research, covering the historical window from 2020 through 2025 and projecting forward to 2032, provides decision-makers with a structured, evidence-based view of where this sector is heading and how to position for it.
Prefabricated Security Booth Market
This article previews the strategic architecture of the study and explains why its findings matter for corporate planning in 2026. The goal is not to deliver every numerical cut in a single page, but to demonstrate the depth of the analysis, the rigor of the methodology, and the actionable frameworks embedded throughout the full report.
Market Trajectory: From Fragmented Growth to Consolidated Scale
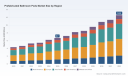
The market has demonstrated steady, compounding expansion over the recent historical period. Revenue grew from approximately 4.32 billion USD in 2020 to 6.7 billion USD by 2025, reflecting both the increasing acceptance of modular construction and the broader push toward schedule compression, labor efficiency, and quality control. Looking ahead, the forecast period from 2026 to 2032 projects continued acceleration, with the market expected to reach 7.24 billion USD in 2026, cross the 10-billion threshold by 2030, and approach 12.59 billion USD by 2032. The compound annual growth rate anticipated across the forecast window sits at 9.4 percent, signaling a sector that is outpacing many traditional construction subsectors.
Such a trajectory cannot be understood through a single lens. Growth is being pulled by multiple overlapping forces: the urgency to reduce on-site labor dependency, the maturation of factory-controlled quality systems, and the growing mandate for repeatable, code-compliant interior units that can be delivered in volume. At the same time, the market remains structurally attractive because it rewards early positioning in manufacturing capacity, logistics networks, and regional partnership ecosystems. The research unpacks how these dynamics interact across the forecast horizon, providing executives with a defensible basis for capacity planning, M&A screening, and route-to-market decisions.
Structural Drivers Shaping the 2026 Decision Environment
Several operational and regulatory forces are now firmly embedded in the market's behavior, and the study connects them directly to commercial outcomes.
- Schedule compression and labor economics. Prefabricated bathroom pods can accelerate project timelines by 40 to 50 percent while reducing on-site workforce needs compared with traditional stick-built methods. For programs where schedule risk carries heavy financial penalties, that performance edge has moved from a bonus to a requirement.
- Code compliance as a competitive moat. Manufacturers increasingly design units that align with local building codes, including International Building Code and IRC frameworks, as well as plumbing regulations, to ensure factory readiness for final on-site inspection. The research examines how compliance readiness affects bidder qualification, procurement preference, and project risk allocation.
- Fire and loss-prevention standards. Loss Prevention Standards such as LPS 1207 now require fire-retardant coverings for temporary packaging and protective materials used during transport and storage of modular bathroom units. This detail matters for logistics planning, packaging design, and supplier qualification, and the report maps it against operational workflows.
- Material performance trade-offs. Steel-based pods continue to hold a strong position in the product mix, with industry data indicating a category share near 34.7 percent, supported by structural strength that enables faster installation and load-bearing capacity for multi-story applications. At the same time, GRP bathroom pods are emerging as a preferred option for their lightweight properties, corrosion resistance, and reduced maintenance requirements relative to traditional materials. The full analysis compares these material pathways across cost, durability, installation speed, and end-market fit.
Report Coverage: What Decision-Makers Will Find Inside
The full market research is built for practical use rather than abstract description. It is designed to support market entry assessments, product-line planning, bidding strategy, and regional expansion analysis. Below is a structured overview of what the study delivers.
Market Sizing and Forecasts
The report presents historical and forecast revenue data across the 2020 to 2032 window in USD billions, with a clearly defined base year, historical period, and forecast horizon. Rather than offering a single top-line number, the analysis separates the market into actionable segments so that executives can identify where growth is concentrated and where competitive intensity is rising.
Segmentation That Supports Planning
The study breaks the market down by region, by type, and by application. These views help teams answer questions such as which geographic markets are expanding most rapidly, how product categories are positioned against each other, and which end-use sectors are driving demand for modular bathroom units. The regional discussion covers North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The product-type view contrasts GRP bathroom pods, steel bathroom pods, and other variants. The application view distinguishes residential, commercial, and additional use cases. Percentages and localized revenue figures are reserved for the full report, where they can be examined alongside competitive context and demand drivers.
Competitive Landscape and Positioning
The research profiles leading manufacturers and maps how each player competes on production capacity, product design, regional reach, and vertical integration. Representative companies include Walker Modular in the United Kingdom, Offsite Solutions in the United Kingdom, Bathsystem S.p.A. in Italy, Interpod in Australia, SurePods in the United States, BAUDET in France, B&T Manufacturing in the United States, Hydrodiseño in Spain, Durapods in the United States, and Loom Crafts in India. These profiles do not stop at company descriptions; they connect manufacturing approaches, product architectures, and target sectors to the broader competitive structure of the market, including concentration indicators that show how share is distributed among top players.
Recent Developments and Strategic Signal
The study integrates recent company-level activity to show how the competitive field is moving in real time. Recent developments captured in the research include Offsite Solutions' February 2026 introduction of a next-generation steel-framed bathroom pod line with modular design elements that allow customization of layouts and finishes while preserving manufacturing efficiency. The same analysis tracks BAUDET's March 2026 project deliveries across multiple hotel modernizations and student residence projects, including work with the Louvre Hotels Group in Paris as well as student residence projects in Saint-Étienne and Caen. The report also notes broader industry events, such as Southwest Solutions Group's April 2026 participation in modular construction and restroom solutions events, showcasing code-compliant prefabricated bathroom pods for fast deployment. Together, these developments illustrate how product innovation, project wins, and industry engagement are reshaping market positioning.
Commercial and Operational Frameworks
Beyond sizing and profiling, the research provides decision frameworks for evaluating manufacturing readiness, compliance alignment, logistics complexity, and demand quality by segment. These frameworks are intended to help teams convert market intelligence into procurement choices, capacity investment plans, and partnership strategies. The full report also includes the analytical detail needed to compare product types, applications, and regions side by side without relying on generic industry narratives.
Why This Research Matters for 2026 Strategy
The 2026 decision environment calls for more than directional confidence. Organizations need to know not only that the market is expanding, but where the growth is coming from, who is capturing it, and what operational capabilities separate scalable players from the rest. The compound annual growth rate of 9.4 percent across the forecast period indicates a sector large enough to attract continued investment, yet fragmented enough that strategic positioning still matters.
For manufacturers, the research supports decisions about production capacity, material mix, customization depth, and regional expansion. For developers and contractors, it clarifies where prefabricated bathroom pods can reduce schedule risk and labor exposure, and how compliance and packaging requirements shape supplier selection. For investors and advisors, it provides the segmentation structure and competitive context needed to evaluate market entry opportunities, consolidation potential, and differentiation pathways.
Prefabricated Bathroom Pods Market
The study is also designed to help teams avoid a common trap: assuming that growth in the aggregate automatically translates into growth for every sub-segment. By separating region, type, and application, the analysis shows where demand is durable, where it is contingent on specific project types, and where competitive overlap is intensifying. That level of granularity is essential in a market where the top three players account for roughly 55 percent of revenue and the top five account for about 68 percent, implying that scale, reputation, and repeat procurement relationships carry significant weight.
What the Full Report Delivers Beyond This Preview
This article is intentionally a framework overview rather than a data dump. The complete market research goes further by providing the detailed segmentation values, regional revenue profiles, product-type comparisons, and application-level demand patterns that executives need for precise planning. It also includes the supporting analysis behind the concentration structure, the competitive profiles, and the recent development timeline.
Readers who want the full strategic picture can access the complete report on our website, where the data tables, segment commentary, company profiles, and development timelines are presented together in a format built for internal discussion and decision-making. The preview above is meant to establish the logic of the analysis and the quality of the evidence, while leaving the specific figures and segment cuts for the full publication.
Closing Perspective
Prefabricated bathroom pods are no longer an alternative construction method; they are becoming a core component of how commercial, residential, healthcare, hospitality, and institutional projects are delivered. The market's recent growth, its projected trajectory through 2032, and the operational advantages embedded in factory-built units all point to a sector that will continue to reward disciplined strategy. This research is designed to give leadership teams the clarity to act on that opportunity with confidence.
For organizations planning investments, procurement shifts, or competitive positioning in 2026, the full market research provides the segmentation detail, competitive context, and development signals needed to move from observation to execution. The complete analysis is available through our official report page, where the underlying market data, company profiles, and strategic frameworks can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Prefabricated Bathroom Pods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium-Sulfur Battery Market to Hit $262.8M by 2032, 25.7% CAGR
By pmarketresearch, 2026-09-15
The Lithium-Sulfur Imperative: Strategic Intelligence for the 2026 Market Inflection
The energy storage landscape is undergoing a structural transformation. After years of incremental improvements in lithium-ion chemistry, the industry is pivoting toward next-generation architectures that promise to decouple performance from cost. Among these, lithium-sulfur technology has moved from laboratory promise to commercial urgency. Our latest market research, spanning historical analysis from 2020 through 2025 and a forward-looking forecast window from 2026 to 2032, captures this transition at precisely the moment when capital allocation, supply chain strategy, and product roadmaps are being locked in for the next decade.
For executives navigating 2026 investment decisions, this report is not a retrospective exercise. It is a decision-support instrument designed to separate signal from noise in a rapidly consolidating landscape where incumbents, startups, and strategic partners are simultaneously racing to scale production, secure raw material advantages, and comply with evolving regulatory frameworks. The insights within are structured to inform go-to-market timing, partnership evaluation, R&D prioritization, and risk hedging across aerospace, automotive, defense, consumer electronics, and stationary storage verticals.
Market Trajectory and the Shape of the Opportunity
The macroeconomic arc of the lithium-sulfur market tells a story of accelerating adoption. Historical revenue tracking from 2020 through 2025 reveals a compounding growth curve that has consistently outpaced earlier projections. The baseline year of 2025 closes at a meaningful inflection point, setting the stage for a forecast period in which the market is projected to expand at a compound annual growth rate of 25.7 percent through 2032. By the end of the forecast window, total market revenue is expected to reach a scale that fundamentally reshapes how investors, OEMs, and policy makers evaluate advanced battery technologies.
This trajectory is not linear extrapolation. It reflects the convergence of multiple structural drivers: the relentless pursuit of higher gravimetric energy density, the economic logic of sulfur-based cathode chemistry, and a regulatory environment that increasingly rewards domestically sourced and low-carbon battery architectures. For strategic planners, the implication is clear. The window for first-mover advantage in specific application segments is narrowing, and the cost of delayed entry is rising as manufacturing capacity begins to materialize and downstream customers start locking in multi-year supply agreements.
What This Report Delivers: An Operational Roadmap
Our research is built around actionable intelligence rather than high-level commentary. Readers will find a comprehensive breakdown of market sizing across the full forecast horizon, with revenue projections calibrated to technology readiness levels, application adoption curves, and regional manufacturing dynamics. The segmentation architecture examines the market through multiple lenses, including type differentiation that distinguishes high-energy-density configurations from lower-density variants, and a detailed application mapping that spans aerospace, automotive, consumer electronics, defense, and energy storage systems.
Beyond sizing, the report delivers a granular competitive landscape analysis. We profile the companies actively shaping the lithium-sulfur ecosystem, evaluating their technological approaches, manufacturing strategies, partnership footprints, and recent commercial moves. The analysis captures the diversity of engineering pathways currently under evaluation, from proprietary three-dimensional graphene architectures and sulfurized-carbon cathodes to nano-encapsulated sulfur formulations, polymer-host anode designs, and thin glass-protected lithium-metal anodes. This comparative framework allows decision makers to benchmark competitor positioning, anticipate consolidation patterns, and identify white spaces where differentiated offerings can command premium positioning.
The report also integrates a forward-looking view of industry dynamics. Regulatory developments, incentive structures, raw material economics, and supply chain considerations are woven into the analysis so that readers can stress-test their strategies against realistic assumptions. This includes an examination of how carbon footprint declaration requirements for industrial rechargeable batteries are reshaping procurement criteria in Europe, how investment tax credit eligibility for hybrid battery energy storage systems continues to support project economics in the United States through 2035, and how long-duration storage cost targets are creating new demand signals for advanced chemistries.
Competitive Architecture: The Battlefield of Lithium-Sulfur Innovation
The competitive field is defined by a mix of well-capitalized startups, specialized technology developers, research institutions, and strategic corporate partners. Several themes emerge from our analysis. First, the race to achieve commercially viable energy density at scale is attracting significant capital and corporate attention. Companies are pursuing divergent technical routes, each with distinct trade-offs in cycle life, manufacturability, safety, and cost structure. This fragmentation is both a risk and an opportunity: it signals that the winning architecture has not yet been universally settled, but it also means that monitoring technical differentiation is essential for partnership and investment decisions.
Lithium-Metal Secondary Battery Market
Recent corporate activity underscores the urgency. In 2025, one of the leading participants began U.S. production of battery-grade lithium-metal foil, a move that completes a localized supply chain for lithium-sulfur batteries and reduces exposure to cross-border component risks. That same company followed with a next-generation drone propulsion system built around American-made lithium-sulfur batteries, targeting national security and defense use cases, and subsequently secured more than 200 million dollars in additional equity investment to accelerate manufacturing expansion and acquisitions. In early 2026, the company entered a binding agreement to acquire a European battery recycling plant, signaling a strategic push to expand lithium-sulfur manufacturing capacity while integrating circular economy considerations into the value chain.
Automotive interest is also crystallizing. A major global automaker announced a joint development agreement with a sulfurized-carbon cathode specialist to co-develop lithium-sulfur EV battery cells with higher gravimetric energy density, an early indicator that large-volume OEMs are moving from observation to active co-engineering. Meanwhile, multiple developers are publicly targeting energy density thresholds that would meaningfully extend electric vehicle range, enable new aviation concepts including eVTOL platforms, and improve the economics of stationary storage deployments. These targets span a wide range, from cell-level configurations approaching 380 Wh/kg to advanced platforms aiming for substantially higher densities, reflecting the breadth of technical ambition in the sector.
Research institutions and government-funded programs remain critical enablers. Several organizations are advancing cycle life and energy density improvements with Department of Energy backing, while pilot production facilities are bridging the gap between laboratory breakthroughs and pilot-scale manufacturing. This ecosystem dynamic means that competitive intelligence must extend beyond commercial manufacturers to include the research and pilot infrastructure that will shape future supply options and technology licensing opportunities.
Market Dynamics: Regulation, Economics, and Supply Chain Realignment
The commercial viability of lithium-sulfur batteries is being shaped as much by policy and input economics as by technical progress. In Europe, regulatory requirements now mandate carbon footprint declarations for industrial rechargeable batteries exceeding 2 kWh capacity, a development that rewards manufacturers with transparent, low-carbon supply chains and creates a compliance differentiator for domestically sourced production. In the United States, the continuation of investment tax credit eligibility for hybrid battery energy storage systems through 2035 sustains project-level economics that favor advanced storage deployments, indirectly supporting demand for higher-performance battery chemistries in stationary applications.
Raw material economics provide another layer of strategic advantage. Sulfur cathode active material costs in lithium-sulfur batteries are reported at approximately 7 cents per kWh, roughly one-third of the equivalent input cost in conventional lithium-ion architectures. This cost asymmetry is a fundamental argument for the long-term competitiveness of the chemistry, particularly in cost-sensitive applications where energy density and material affordability must be balanced. Coupled with domestic sourcing pathways for sulfur and lithium-metal anodes that support tariff-free manufacturing, the input cost structure creates a credible route to price competitiveness as scale increases.
On the demand side, public-sector cost targets are sharpening focus. The Department of Energy's long-duration storage shot aims to reduce the levelized cost of storage to 5 cents per kWh by 2030 through advanced battery technologies, including lithium-sulfur platforms. While this target spans multiple technology pathways, it signals a clear policy direction: advanced chemistries that can deliver low levelized cost at scale will be prioritized in procurement, incentive design, and research funding. For companies and investors, aligning product roadmaps with these cost trajectories is becoming a strategic necessity rather than an optional optimization.
Decision Framework for 2026 and Beyond
As the market moves from early commercialization into a phase of capacity expansion and application-specific scaling, strategic decisions must be grounded in a clear understanding of where value will accrue. Several considerations should guide executive planning. First, the concentration of market share among leading participants remains moderate, indicating that the sector is still in a competitive formation stage rather than a mature oligopoly. This creates room for new entrants, targeted acquisitions, and differentiated positioning, but it also requires disciplined analysis of which technical and commercial pathways are most likely to achieve scale.
Second, application segmentation will not converge uniformly. Aerospace and defense use cases prioritize energy density and supply chain security, automotive applications demand cost-competitive scaling and integration with existing vehicle architectures, and stationary storage deployments weigh levelized cost, cycle life, and regulatory compliance. Our segmentation analysis helps decision makers map these differing requirements to realistic adoption timelines and revenue opportunities, avoiding the trap of treating lithium-sulfur as a single-market proposition.
Third, supply chain strategy is becoming a competitive moat. Companies that can localize critical inputs, integrate recycling capacity, and align with regulatory requirements around carbon transparency are building advantages that extend beyond cell performance. The recent moves toward domestic lithium-metal foil production, European recycling capacity acquisition, and tariff-free input sourcing illustrate how supply chain design is now inseparable from technology strategy.
Why This Research Matters Now
The 2026 to 2032 forecast window is not a distant planning exercise. It is the period during which manufacturing capacity, customer qualification cycles, regulatory compliance costs, and partnership structures will be established. Decisions made in 2026 regarding technology bets, supplier relationships, geographic focus, and application prioritization will determine competitive positioning for the remainder of the decade. Our report is designed to provide the depth, structure, and forward-looking context needed to make those decisions with confidence.
The full study goes beyond summary indicators to deliver the detailed segmentation data, company profiles, regulatory impact assessments, and scenario-based revenue projections that strategic teams require. It is built for executives who need to translate market momentum into concrete action: where to invest, whom to partner with, which applications to prioritize, and how to position against a rapidly evolving competitive set. The macro trajectory is compelling, the technical pathways are diversifying, and the regulatory and cost environment is increasingly favorable. The critical question for 2026 is no longer whether lithium-sulfur batteries will matter, but how decisively an organization will act to capture its share of the opportunity.
Lithium-Sulfur Battery Market
For detailed analysis of this topic, please visit the official page: Lithium-Sulfur Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: eNVM Market to Hit $344.8M by 2032, CAGR 11.54% Driven by Automotive
By pmarketresearch, 2026-09-15
Navigating the Embedded Non-Volatile Memory Landscape: Strategic Intelligence for 2026 and Beyond
The semiconductor industry is currently witnessing a paradigm shift in how data is stored, retained, and accessed at the edge. As artificial intelligence moves from the cloud to the device and connectivity becomes ubiquitous, the demand for resilient, high-performance memory solutions has never been more critical. Embedded Non-volatile Memory (eNVM) stands at the forefront of this transformation, serving as the foundational backbone for microcontrollers, systems-on-chips, and specialized processors. For stakeholders navigating the complex terrain of 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative.
PW Consulting is pleased to introduce our latest comprehensive market research report on the Embedded Non-volatile Memory Market. This document serves as a deep dive into the forces shaping the industry, offering a roadmap for decision-makers who need to align their portfolios with emerging realities. The following insights provide a preview of the strategic value contained within the full study, designed to equip you with the clarity needed to act decisively in a rapidly evolving ecosystem.
The Macro Outlook: Growth Trajectories and Valuation
The financial narrative of the eNVM sector is defined by robust expansion and sustained momentum. Based on extensive historical analysis spanning 2020 through 2025 and a detailed forecast period extending to 2032, the market demonstrates a compelling growth story. The overall market size has shown consistent appreciation over the last half-decade, reflecting the increasing integration of memory into diverse electronic systems. By 2025, the market had solidified its position as a critical component of the semiconductor value chain, with valuation trends indicating a strong upward curve.
Looking toward the forecast horizon from 2026 to 2032, the projected Compound Annual Growth Rate (CAGR) underscores the vitality of this sector. The data suggests that the market will continue to expand at a pace that outpaces many traditional semiconductor segments. This growth is not linear but is driven by specific technological inflection points and adoption waves across key industries. The revenue projections through the early 2030s indicate a market that is not only growing in value but also in strategic importance, as non-volatile storage becomes integral to the functionality of smart devices, autonomous systems, and industrial automation.
Technology Segmentation and Application Diversity
The eNVM landscape is not monolithic. It is characterized by a diverse array of technologies, each catering to specific performance, power, and cost requirements. The market is primarily segmented by technology type, with established solutions like embedded Flash and EEPROM maintaining significant footholds. However, the periphery of this segment is where the most dynamic innovation is occurring. Emerging technologies such as Resistive RAM (ReRAM), Magnetoresistive RAM (MRAM), Phase Change Memory (PCM), and Ferroelectric RAM (FRAM) are gaining traction, driven by the need for lower power consumption, higher endurance, and faster write speeds.
Each technology type solves a specific set of engineering challenges. For instance, while traditional flash remains dominant in certain cost-sensitive applications, next-generation non-volatile memories are becoming essential for high-performance computing and harsh environment operations. The report provides a granular analysis of these technology splits, examining the revenue contributions and growth vectors for each category. It explores how the shift from standard CMOS pathways to specialized fabrication processes influences the viability and adoption rates of these newer memory formats.
Beyond technology, the application landscape is a key driver of demand. The automotive sector represents a substantial portion of the market, fueled by the electrification of vehicles and the rise of advanced driver-assistance systems. Consumer electronics continue to be a steady contributor, driven by the proliferation of smart home devices and wearables. Meanwhile, the Internet of Things (IoT) and industrial sectors are emerging as critical growth engines, requiring memory solutions that can withstand extreme conditions and support edge computing capabilities. The research detailed in this report dissects these application verticals, highlighting the unique memory requirements and adoption trends within each domain.
Geographic Dynamics and Regional Influence
Geographic factors play a pivotal role in the distribution and consumption of eNVM solutions. The market is globally distributed, with significant concentration in key regions that host major semiconductor fabrication capabilities and end-market demand. Asia Pacific remains a dominant force, reflecting the region's extensive manufacturing infrastructure and large consumer base. North America and Europe follow, each with distinct market characteristics driven by local industrial policies, automotive hubs, and technological innovation centers.
Automotive Embedded Storage (eMMC and UFS) Market
Emerging regions, including Latin America and the Middle East and Africa, also contribute to the global footprint, though at different scales. The report analyzes these regional dynamics to help stakeholders understand where demand is concentrated and where supply chain vulnerabilities may exist. Understanding the geographic flow of eNVM products is essential for supply chain optimization and market entry strategies. The full study provides a detailed regional breakdown, offering insights into local market sizes and growth rates without exposing the raw segmentation data publicly, ensuring that our clients gain a competitive edge through exclusive access to precise figures.
Embedded Non-volatile Memory (eNVM) Market
Competitive Landscape and Key Industry Players
The competitive arena of the eNVM market is populated by a mix of established semiconductor giants, specialized memory manufacturers, and foundry service providers. The market concentration metrics indicate a landscape where no single entity holds absolute dominance, allowing for a dynamic environment of innovation and strategic partnerships. The CR3 and CR5 ratios suggest a moderately fragmented but highly competitive space, where differentiation is achieved through technology leadership and integration capabilities.
Samsung Electronics continues to be a formidable presence, developing and manufacturing embedded STT-MRAM and flash eNVM solutions for MCUs, SoCs, and high-performance applications. Their ability to scale advanced memory technologies positions them as a key enabler for next-generation devices. STMicroelectronics has carved a niche by integrating embedded PCM and RRAM eNVM into 18nm FD-SOI MCUs, specifically targeting automotive and industrial use cases where reliability is paramount. Similarly, Infineon Technologies provides embedded FRAM and RRAM eNVM in automotive AURIX controllers and edge ML microprocessors, reinforcing the link between memory technology and functional safety.
NXP Semiconductors delivers embedded MRAM eNVM in 16nm FinFET automotive MCUs developed with TSMC, showcasing the importance of foundry partnerships in enabling advanced node integration. Renesas Electronics offers embedded STT-MRAM and flash eNVM for industrial and IoT MCUs, addressing the needs of smart infrastructure and automation. Texas Instruments supplies embedded ferroelectric and flash eNVM in MCUs and processors, maintaining a broad portfolio that serves diverse customer bases. Microchip Technology manufactures embedded flash and NOR eNVM for embedded systems and MCUs, focusing on reliability and extensive product availability.
On the innovation frontier, companies like Weebit Nano are licensing embedded ReRAM IP for integration into foundry platforms such as 130nm BCD and 22nm nodes. Their recent activities highlight the momentum in IP licensing models. In April 2025, Weebit Nano demonstrated chips integrating embedded ReRAM in DB HiTek's 130nm BCD process for mixed-signal and high-voltage applications. Earlier in the year, they qualified ReRAM IP for Sky Water Technology's 130nm CMOS platform and secured a licensing agreement with onsemi for integration into the Treo platform targeting automotive and industrial applications. Everspin Technologies has also expanded its PERSYST MRAM portfolio with high-reliability products qualified for automotive and aerospace, including the EM064LX HR and EM128LX HR.
Foundry partners play a crucial role in this ecosystem. TSMC embeds MRAM and ReRAM eNVM directly into advanced 22nm and 12nm FinFET processes for MCUs and SoCs, enabling customers to access cutting-edge memory integration. GlobalFoundries integrates embedded MRAM and ReRAM eNVM into 12nm and 22FDX platforms for high-reliability designs, catering to sectors that demand exceptional performance under stress. These collaborations between memory IP providers, device manufacturers, and foundries are essential for overcoming the integration complexity that characterizes this market.
Industry Dynamics: Challenges and Enablers
The path to widespread eNVM adoption is not without obstacles. High manufacturing costs and complex integration processes for eNVM require specialized fabrication equipment that diverges from standard CMOS pathways. This divergence can create barriers to entry and influence cost structures for end products. Embedding eNVM into next-generation SoCs requires unique layout designs, extra IP blocks, and extended verification periods that extend development timelines. These factors necessitate careful planning and investment from companies looking to incorporate advanced memory solutions into their designs.
Regulatory and qualification standards also shape the market dynamics. Automotive and industrial eNVM products must meet AEC-Q100 Grade 1 qualification with operation from -40°C to +125°C and minimum 10-year data retention. Meeting these stringent requirements adds to the complexity and cost but is non-negotiable for safety-critical applications. Additionally, radiation-hardened embedded NVM options require specialized material platforms and testing processes to meet aerospace and high-reliability standards. These certification and qualification hurdles serve as moats for established players while creating opportunities for those who can navigate the regulatory landscape efficiently.
Geopolitical factors also influence the market. Chinese semiconductor foundries such as SMIC and UMC actively supply embedded MRAM and ReRAM eNVM to global manufacturers. This supply chain diversification has implications for risk management and sourcing strategies. Companies must balance the benefits of access to advanced technology with the need to mitigate geopolitical risks and ensure supply chain resilience. The report delves into these dynamics, providing context on how external forces impact market structure and strategic decision-making.
Strategic Value of the Full Report
While the overview above highlights the breadth of the eNVM market, the full PW Consulting report offers depths that are essential for precise strategic planning. This document is not merely a collection of data points; it is a strategic tool designed to answer the critical questions facing executives, product managers, and investors. How will the shift toward edge AI impact memory requirements? Which technology nodes will dominate the automotive sector in the next five years? Where are the highest growth opportunities for IP licensors versus device manufacturers?
The report includes detailed financial models, technology roadmaps, and competitive profiling that allow readers to benchmark their positions against industry leaders. It provides actionable insights on supply chain optimization, partnership opportunities, and R&D prioritization. For those involved in mergers and acquisitions, the market concentration data and growth trajectories offer valuable context for valuation and due diligence. For product developers, the analysis of integration complexity and qualification requirements can inform design-in decisions and time-to-market strategies.
By accessing the complete study, stakeholders can move beyond general trends to specific, data-backed conclusions. The full report contains the meticulous segmentation by type, application, and region that allows for targeted market sizing and revenue forecasting. It explores the nuances of regional policies, local manufacturing capabilities, and consumption patterns that drive global trade flows. This level of detail is crucial for avoiding generic strategies and instead implementing plans that are tailored to the specific realities of the eNVM ecosystem.
Conclusion: Positioning for the Future
The Embedded Non-volatile Memory Market is poised for significant transformation as we move through 2026 and beyond. The convergence of IoT, automotive electrification, and edge computing is creating a perfect storm of demand that rewards innovation and strategic foresight. Companies that can navigate the complexities of technology integration, manage supply chain risks, and align their offerings with the evolving needs of end markets will be best positioned to capture value in this growing sector.
PW Consulting's latest market research report on eNVM is designed to be your companion in this journey. It provides the intelligence needed to make informed decisions, mitigate risks, and identify opportunities that might otherwise remain hidden in the noise of a rapidly changing industry. We invite you to access the full report to unlock the comprehensive data and analysis that will empower your organization to lead in the era of embedded intelligence. The future of memory is being written now, and with the right insights, you can ensure your strategy is aligned with the trajectory of growth and innovation.
For detailed analysis of this topic, please visit the official page: Embedded Non-volatile Memory (eNVM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogen Fuel Cell GDL Market Hits $2B in 2025, Surges to $4B by 2032 at 13.18% CAGR
By pmarketresearch, 2026-09-15
Navigating the Hydrogen Fuel Cell Gas Diffusion Layer Market: Strategic Intelligence for 2026 and Beyond
The transition toward net-zero economies has placed hydrogen fuel cells at the center of global decarbonization strategies. Within the intricate architecture of a proton exchange membrane fuel cell, the Gas Diffusion Layer serves as a critical interface between the flow field and the catalyst layer. This thin, porous component is responsible for distributing reactant gases evenly, managing water removal, and facilitating electron transport. As the industry scales from niche applications to mass deployment, the Gas Diffusion Layer market has emerged as a high-stakes battleground for materials science, supply chain resilience, and strategic positioning.
PW Consulting's latest market research publication provides a comprehensive, data-driven analysis of this evolving landscape. Designed for executives, investors, and strategic planners, this report dissects the market dynamics, competitive structures, and technological shifts that will define the sector through 2032. The following analysis outlines the core insights and strategic value embedded within the full study, offering a clear preview of the intelligence required to navigate the complexities of 2026 and the forecast period ahead.
Market Trajectory and Growth Dynamics
The hydrogen economy is transitioning from policy-driven pilots to commercially viable deployments. This shift is reflected in the robust expansion of the Gas Diffusion Layer market. In 2025, the sector reached a valuation of approximately 2,000.0 million USD, a substantial increase driven by accelerating automotive fuel cell deployments, growing stationary power installations, and the maturation of portable power applications. Forecasts indicate that this momentum will continue, with the market projected to reach 2,271.54 million USD in 2026 and eventually surpass the 4,000.0 million USD threshold by 2032.
Worldwide Bipolar Plate Fuel Cell Market
Our analysis identifies a compound annual growth rate of 13.18 percent across the 2026 to 2032 forecast period. This trajectory is not merely a continuation of historical trends but is underpinned by structural changes in manufacturing capacity, regional demand surges, and the diversification of end-use applications. The historical segment from 2020 to 2025 demonstrates a clear acceleration, with annual revenues climbing from 700.0 million USD to over 2,000.0 million USD. This compound growth reflects the sector's maturation, moving beyond experimental prototypes into scalable production environments where reliability, cost efficiency, and supply chain stability are paramount.
Strategic Implications of Growth Patterns
The forecasted growth rate carries significant implications for procurement strategies, capacity planning, and competitive positioning. Companies that recognize the inflection point in demand will be better positioned to secure long-term supply agreements, invest in advanced manufacturing capabilities, and capitalize on regional demand shifts. The market's trajectory also highlights the increasing importance of material innovation. Traditional gas diffusion layers have relied on carbon fiber paper treated with perfluorinated hydrophobic agents such as PTFE. However, academic research and industrial development are increasingly exploring fluorine-free alternatives, including interpenetrating networks of graphene, cellulose fiber, and modified polypropylene fiber. These innovations promise to address environmental concerns, reduce reliance on fluorinated compounds, and potentially lower production costs over the long term.
Competitive Landscape and Industry Concentration
The Gas Diffusion Layer market is characterized by a moderately concentrated competitive structure. Our analysis indicates that the top three firms command a combined market share of 60.0 percent, while the top five players collectively hold 70.0 percent of the market. This concentration underscores the dominance of established materials science and carbon fiber specialists who have leveraged decades of experience in advanced composites to secure strong positions in the hydrogen fuel cell supply chain. At the same time, the remaining market share is distributed among specialized manufacturers, regional suppliers, and innovative startups that are differentiating themselves through material substitutions, performance enhancements, and targeted application segments.
Key Players and Strategic Positioning
The competitive field is led by a cohort of globally recognized companies, each bringing distinct technological capabilities and regional strengths to the table. SGL Carbon, headquartered in Germany, is a pioneer in carbon-based solutions and produces SIGRACET carbon paper and carbon cloth gas diffusion layers with microporous layer and PTFE treatments tailored for PEM hydrogen fuel cells. In a notable move toward sustainability, SGL Carbon announced a new pilot line in Germany that uses recycled carbon fibers for GDL production, aiming to reduce raw material waste by up to 40 percent. This initiative reflects a broader industry push to align manufacturing practices with circular economy principles and regulatory expectations.
Toray Industries, based in Japan, manufactures Torayca carbon paper GDL products for PEM fuel cells and water electrolyzers. The company showcased its Torayca GDL for PEM fuel cells and Torayca carbon paper for PEM water electrolyzers at the Hydrogen Technology World Expo 2025, reinforcing its commitment to serving both fuel cell and electrolysis ecosystems. Freudenberg Group, also based in Germany, provides a comprehensive range of Freudenberg fuel cell gas diffusion layers, encompassing both carbon cloth and paper types, and has built a reputation for reliability in demanding automotive and stationary applications.
AvCarb LLC, operating from the United States, offers the MGL series of carbon cloth gas diffusion layers specifically engineered for hydrogen fuel cell applications. Caplinq Corporation, another US-based supplier, provides LINQCELL carbon paper, graphitized carbon paper, and conductive plastic GDL products, catering to research, development, and commercial production needs. Technical Fibre Products Ltd, based in the United Kingdom, develops and produces carbon fiber cloth and felt gas diffusion layers, leveraging deep expertise in carbon fiber processing. Mitsubishi Chemical Corporation, headquartered in Japan, supplies GDL materials and components for hydrogen fuel cell systems, integrating material science capabilities with broader industrial chemical expertise.
Additional players further enrich the competitive landscape. Fuel Cells Etc, a US-based retailer and provider, supplies Sigracet, ELAT, and other carbon cloth and paper GDL products, serving both commercial and research markets. Mott Corporation, also based in the United States, manufactures porous GDL substrates and related fuel cell materials, focusing on engineered porosity and custom substrate solutions. GKD Gebr. Kufferath AG, headquartered in Germany, produces mesh-based gas diffusion layers for fuel cell applications, offering alternative structural approaches to gas distribution and water management.
Hydrogen Fuel Cell Gas Diffusion Layer Market
Supply Chain Dynamics and Regulatory Pressures
The market's growth is occurring against a backdrop of evolving geopolitical and regulatory dynamics. Trade constraints between the United States and China have the potential to disrupt supply chains for critical GDL components, particularly those relying on specialized precursors, manufacturing equipment, or intermediate materials sourced from Asia. These constraints necessitate a proactive approach to supply chain diversification, regional sourcing strategies, and inventory resilience. Companies that fail to anticipate these disruptions risk cost escalations, production delays, and loss of competitive advantage in key end markets.
Simultaneously, the European Union's push for green energy policies and possible trade barriers for GDL materials introduces additional complexity. Regulatory frameworks aimed at reducing carbon footprints, promoting circular economy practices, and ensuring sustainable material sourcing are reshaping procurement requirements and manufacturing standards. The environmental performance of gas diffusion layers, including the use of fluorinated agents and the recyclability of carbon fiber substrates, is increasingly scrutinized. This regulatory environment favors suppliers that can demonstrate compliance with emerging sustainability criteria, invest in cleaner production processes, and adapt to evolving trade policies.
Raw material considerations also play a pivotal role in market dynamics. Traditional GDLs are comprised of carbon fiber paper treated with perfluorinated hydrophobic agents such as PTFE. While these materials have proven effective in managing water repellency and gas distribution, the industry is exploring alternatives that reduce or eliminate fluorine content. The development of fluorine-free bulk hydrophobic GDLs with interpenetrating networks of graphene, cellulose fiber, and modified polypropylene fiber represents a significant technological frontier. These innovations could alter material cost structures, simplify recycling processes, and align GDL production with stricter environmental regulations.
Market Segmentation: Type, Application, and Regional Drivers
Understanding the market's structural composition is essential for identifying growth opportunities and optimizing product portfolios. The segmentation analysis reveals distinct patterns across material types, application sectors, and geographic regions, each with unique drivers and competitive dynamics.
Material Type Dynamics
The market is segmented by material type into carbon paper, carbon cloth, and other specialized variants. Carbon paper remains the dominant material category, reflecting its widespread adoption in high-volume automotive and stationary power applications where cost efficiency, mechanical stability, and consistent performance are critical. Carbon cloth offers distinct advantages in terms of flexibility, compressibility, and gas permeability, making it particularly suitable for certain portable power applications and specialized fuel cell designs. The other types segment encompasses emerging material configurations, including hybrid structures, metal-based substrates, and advanced composites that address specific performance or cost requirements. Each type presents different manufacturing challenges, supply chain considerations, and end-use suitability, requiring companies to maintain a diversified material portfolio to capture demand across multiple segments.
Application Segment Opportunities
The application landscape is divided among automotive, stationary power generation, and portable power. Automotive applications represent the largest demand driver, fueled by the continued rollout of fuel cell electric vehicles, commercial fleet deployments, and infrastructure expansion. Stationary power generation constitutes a significant and growing segment, driven by backup power systems, microgrid solutions, and industrial decarbonization initiatives where fuel cells provide reliable, low-emission electricity. Portable power applications, while smaller in absolute terms, serve niche markets such as military equipment, remote telecommunications, and specialized consumer devices, where lightweight, high-energy-density power sources are essential. Each application segment demands different performance characteristics, durability standards, and cost structures, influencing the design, material selection, and manufacturing approach for gas diffusion layers.
Regional Demand Patterns
Geographic diversification is a defining feature of the market. Demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with each region exhibiting distinct drivers, regulatory environments, and competitive intensities. Asia Pacific stands out as a major growth engine, supported by aggressive hydrogen strategies, large-scale manufacturing investments, and rapid adoption of fuel cell technologies in both transportation and stationary power. North America and Europe continue to play pivotal roles, driven by policy incentives, stringent emissions targets, and a strong presence of technology leaders and research institutions. Latin America and the Middle East and Africa represent emerging opportunities, where hydrogen initiatives are gaining momentum and infrastructure development is gradually expanding the addressable market for fuel cell components. Companies operating in this landscape must tailor their market entry strategies, supply chain configurations, and product positioning to the specific regulatory, economic, and demand conditions of each region.
Report Scope and Operational Relevance
The PW Consulting Hydrogen Fuel Cell Gas Diffusion Layer Market report is designed to deliver actionable intelligence that supports strategic decision-making across multiple functional areas. The study provides a detailed examination of market size, growth trajectories, segmentation patterns, competitive positioning, and industry dynamics, equipping executives with the data and context needed to formulate effective strategies.
Core Analytical Components
The report encompasses a thorough assessment of historical performance and forecast projections, enabling readers to contextualize current market conditions and anticipate future developments. It includes a granular segmentation analysis that dissects demand by material type, application, and region, highlighting the relative weight and growth characteristics of each segment. Competitive analysis profiles key market participants, examining their product portfolios, technological capabilities, strategic initiatives, and market share positions. The study also evaluates recent developments and industry events that shape the competitive environment, including capacity expansions, trade show demonstrations, material innovation announcements, and regulatory changes.
Operational and Strategic Applications
For procurement and supply chain teams, the report offers insights into material availability, supplier landscape, and cost drivers, supporting sourcing decisions and risk mitigation strategies. For product development and engineering leaders, the analysis of material types, technological trends, and application requirements provides a foundation for innovation roadmaps and performance optimization. For business development and commercial teams, the segmentation and regional analysis helps identify high-growth opportunities, prioritize market entry initiatives, and tailor value propositions to specific customer segments. For executive leadership and investors, the competitive concentration analysis, growth projections, and regulatory context inform long-term positioning, portfolio allocation, and risk assessment.
The report also addresses the practical challenges of scaling production, managing raw material dependencies, and navigating trade and regulatory complexities. It highlights the importance of aligning manufacturing capabilities with demand patterns, investing in material innovation to stay ahead of regulatory shifts, and building supply chain resilience in an environment of geopolitical uncertainty. By integrating market data, competitive intelligence, and industry context, the study provides a holistic view of the factors that will influence success in the hydrogen fuel cell gas diffusion layer market through 2032.
Strategic Imperatives for 2026 and Beyond
As the market advances toward the mid-2020s, several strategic imperatives emerge for companies operating in or adjacent to the hydrogen fuel cell gas diffusion layer ecosystem. First, securing reliable access to high-quality materials and manufacturing capacity is essential. The concentration of market share among leading suppliers underscores the need for strong supplier relationships, long-term agreements, and, where feasible, vertical integration or strategic partnerships to ensure supply continuity. Second, monitoring and adapting to regulatory changes, particularly around fluorinated materials, recycling requirements, and trade policies, will be critical to maintaining compliance and competitive relevance. Third, investing in material innovation and process optimization offers a pathway to differentiation, cost reduction, and alignment with sustainability goals. Fourth, regional strategy must be nuanced, recognizing that demand drivers, regulatory environments, and competitive intensities vary significantly across geographies.
The hydrogen fuel cell gas diffusion layer market is at an inflection point. Growth is accelerating, competition is intensifying, and the technological and regulatory landscape is evolving rapidly. Companies that approach this environment with rigorous analysis, strategic foresight, and operational agility will be best positioned to capture value and drive long-term success.
This overview provides a structured preview of the insights contained within the full PW Consulting market research report. For detailed segmentation data, complete competitive profiles, quantified regional and application breakdowns, and comprehensive forecast models, we invite stakeholders to access the full study. The complete intelligence package is designed to support precise strategic planning, informed investment decisions, and confident navigation of the hydrogen fuel cell gas diffusion layer market in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hydrogen Fuel Cell Gas Diffusion Layer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Footwear Market Hits $483B in 2025, Projected 4.7% CAGR to Reach $663.9B by 2032
By pmarketresearch, 2026-09-15
Navigating the Future of Footwear: Strategic Intelligence for 2026 and Beyond
The global footwear market stands at a critical inflection point. As brands confront shifting trade policies, evolving sustainability mandates, and rapidly changing consumer preferences, the margin between reactive adaptation and proactive strategy has never been thinner. PW Consulting’s latest Footwear Market research study is designed to cut through the noise, delivering a rigorous, data-anchored framework that equips executives, investors, and product leaders with the intelligence needed to make decisive moves throughout 2026 and the forecast horizon through 2032.
This article outlines the study’s analytical architecture, highlights the structural forces reshaping the sector, and demonstrates how decision-makers can translate macro-level market intelligence into operational advantage. The complete dataset, granular segmentation breakdowns, and proprietary competitive matrices are reserved for the full report. What follows is a strategic preview of the terrain ahead.
Market Architecture: A Trajectory of Measured Expansion
Historical performance from 2020 through 2025 illustrates a sector that has consistently weathered macroeconomic headwinds while expanding its revenue footprint. The market progressed from a base of $389.5 billion in 2020 to $424.66 billion in 2021, steadied at $436.1 billion in 2022, and continued its upward march to $445.45 billion in 2023 and $465.26 billion in 2024. By 2025, total revenue reached $483.0 billion, establishing a robust foundation for the forecast period.
Looking ahead, the trajectory projects sustained, compounding growth. The market is expected to cross $506.5 billion in 2026, advance to $532.4 billion in 2027, and approach $559.8 billion by 2028. Continued expansion is anticipated through 2029 ($566.9 billion), 2030 ($585.9 billion), 2031 ($628.9 billion), and culminating at $663.9 billion in 2032. Across the 2025–2032 forecast window, the sector is positioned to deliver a compound annual growth rate of 4.7 percent in USD terms.
Sports Footwear Market
This growth profile is neither explosive nor stagnant; it is structural. The consistent upward slope suggests that underlying demand drivers—fitness participation, casualization trends, and durable replacement cycles—are compounding even as pricing pressures and supply chain realignments introduce volatility. Our research deciphers where that growth concentrates, which customer cohorts are accelerating or decelerating, and how the balance of power is shifting across geographies and product architectures.
The Strategic Terrain: Dynamics Shaping 2026 Decision-Making
Three intersecting forces define the current operating environment for footwear manufacturers, distributors, and retailers. Understanding their interplay is essential for building resilient portfolios and defensible margin structures.
Trade Policy and Cost Architecture
Regulatory and tariff environments have transitioned from peripheral considerations to central boardroom topics. U.S. footwear tariffs average approximately 23.6 percent, with specific categories facing duties exceeding 48 percent. In 2025 alone, industry participants remitted $6.221 billion in tariffs, a figure that underscores how trade policy now functions as a direct line item in cost structures and pricing strategies. Global brands and suppliers have responded by recalibrating sourcing footprints, with acquisition activity increasing in 2025 as companies seek to offset cost impacts and secure domestic or nearshore capacity. McKinsey’s latest outlook also projects low single-digit growth for the broader global fashion industry in 2026, with footwear identified as a key subsector navigating tariff uncertainty.
For strategic planners, the implication is clear: cost modeling must incorporate dynamic duty scenarios, and supply chain flexibility is no longer a premium feature but a baseline requirement. The analysis in our study maps how these pressures interact with segment-level pricing power and margin retention strategies, without exposing the proprietary allocation figures that would enable direct benchmarking.
Sustainability Mandates and Product Traceability
Regulatory frameworks are increasingly tying market access to verifiable sustainability performance. The EU Ecodesign for Sustainable Products Regulation mandates Digital Product Passports for footwear by 2027, a requirement designed to enhance traceability, material transparency, and lifecycle accountability. Compliance will affect everything from design specifications and supplier qualification to consumer-facing claims and inventory management systems.
Simultaneously, product innovation is converging with sustainability. Recent trade show activity, including the Footwear Show New York Expo held in June 2026, showcased sustainable innovations, sculptural heels, and minimalist sneakers as focal points for buyer engagement. Similarly, the 26th International Shoes & Leather Exhibition in Ho Chi Minh City, scheduled for July 2026, is positioned to highlight new machinery, advanced materials, and sustainable footwear initiatives across the Asia-Pacific production ecosystem. These signals suggest that sustainability is transitioning from a compliance checkbox to a product differentiation lever and a procurement prerequisite. Our report dissects how leading manufacturers are operationalizing these mandates and which material and process innovations are gaining commercial traction.
Consumer Behavior and Demand Realignment
Consumer spending patterns continue to reflect a nuanced recovery. Footwear and accessories led outdoor retail sales growth in 2024 according to Outdoor Industry Association data, with a modest rebound extending into 2025. This trend highlights the resilience of activity-driven purchasing, even as broader discretionary spending remains selective. At the same time, category preferences are shifting: athletic and lifestyle products are competing more aggressively for share, casual comfort is consolidating its everyday role, and formal segments are recalibrating around occasion-driven demand.
Demand is also fragmenting across demographics and use cases, requiring more granular assortment planning and inventory positioning. The study evaluates which consumer cohorts are expanding spend, how occasion and activity segmentation influences repeat purchase behavior, and where channel mix is reshaping fulfillment economics. These insights are structured to inform assortment strategy, promotional cadence, and regional prioritization without disclosing the exact allocation values that form the backbone of the full dataset.
Competitive Landscape: Concentration, Positioning, and Ecosystem Evolution
The footwear market operates with moderate but meaningful concentration. The top three players account for approximately 52 percent of market revenue, while the top five collectively represent around 58 percent. This structure creates a landscape where scale advantages coexist with specialized niches, and where competitive differentiation increasingly depends on design velocity, comfort engineering, vertical integration, and compliance capability.
The competitive field spans multiple strategic archetypes. Global athletic and lifestyle franchises—including Nike, Inc., Puma SE, adidas America, Inc., ASICS America, and New Balance—continue to anchor the performance and lifestyle segments, each pursuing distinct design philosophies, distribution models, and brand ecosystems. In the casual and comfort space, Crocs, Inc., Skechers USA Inc., and Clarks maintain strong consumer recognition, while ECCO Sko A/S and Geox S.p.A. emphasize premium casual positioning and breathable comfort technologies, respectively. Rieker Shoes and Belleville Boot Company further illustrate the breadth of specialization, with orthopedic comfort and tactical/military applications representing distinct demand pools.
Beyond consumer-facing brands, a parallel ecosystem of work, outdoor, safety, and military-focused manufacturers underscores the strategic importance of compliance and durability. Timberland LLC, Danner Shoe Manufacturing Company, Red Wing Shoe Company, and Wolverine World Wide Inc. anchor the work and outdoor categories, while McRae Industries and Belleville Boot Company highlight Berry Amendment-compliant military combat boot production, a niche where regulatory adherence and supply chain reliability are as critical as product performance. Steinberg Systems contributes additional depth in work and safety footwear manufacturing. Brooks Running specializes in running and performance athletic footwear, reinforcing the segmentation between mass-market lifestyle lines and application-specific engineering. A newer generation of innovators, including Made Plus, is entering the field with next-generation performance footwear that pairs advanced design with sustainability mandates, signaling how product architecture is evolving to meet both consumer expectation and regulatory scrutiny.
Recent membership and ecosystem developments further illustrate how the competitive landscape is being reshaped by supply chain localization and capacity expansion. In May 2026, McRae Industries was welcomed as the newest USFMA manufacturer member, reinforcing its legacy in Berry Amendment-compliant military combat boots. In April 2026, YKK Americas joined USFMA to expand national capacity for military boot production following the acquisition of Collt’s Manufacturing. In February 2026, Gusbi, Autec Automation, and Robot System Automation were added as Italian footwear machinery leaders to enhance U.S. production capacity for domestic manufacturers. These movements point to a broader shift: capabilities in compliant manufacturing, automation, and domestic sourcing are becoming strategic differentiators, not just operational utilities. The full report provides a comparative analysis of how key players are aligning product portfolios, sourcing strategies, and compliance capabilities to protect share and capture growth.
Inside the Study: Analytical Depth Built for Executive Action
This research is structured to move beyond surface-level trend summaries and deliver an operational intelligence toolkit. The study integrates historical performance, forward-looking forecasts, and multi-dimensional segmentation to give decision-makers a coherent view of where value is created and how competitive advantage is sustained.
Coverage Architecture
The report maps the market across a defined historical window and a seven-year forecast horizon, providing continuity between past performance and future expectation. It decomposes total market revenue across product type, consumer application, and regional demand patterns, enabling readers to identify where structural growth is most durable and where cyclical vulnerabilities may emerge. Rather than presenting isolated statistics, the analysis connects segmentation behavior to pricing dynamics, channel economics, and competitive positioning.
Operational Components
Strategic users will find several layers of actionable content:
- Macro and segment-level growth pathways that link historical momentum to forecast assumptions, allowing teams to stress-test planning scenarios.
- Competitive positioning frameworks that map how leading players differentiate across design, performance, comfort, compliance, and distribution, with attention to the structural advantages implied by market concentration.
- Regulatory and trade impact analysis that translates tariff exposure, sustainability mandates, and traceability requirements into strategic implications for sourcing, product design, and cost architecture.
- Consumer and channel dynamics that contextualize demand shifts across activity-driven, lifestyle, and occasion-based purchasing, helping brands refine assortment strategy and inventory allocation logic.
- Ecosystem and capacity developments that track machinery investment, domestic production expansion, and membership-driven supply chain realignment, offering early signals of where operational bottlenecks may ease or intensify.
Each component is designed to be integrated into existing strategic planning processes. The report’s format supports scenario modeling, competitive benchmarking, and investment prioritization, while the underlying methodology ensures consistency between historical baselines and forward projections.
Why the Full Dataset Matters
Market intelligence reaches its full value only when it is granular enough to inform specific decisions. Segment-level allocation figures, regional demand patterns, and type- and application-level revenue splits form the operational backbone that allows teams to compare internal performance against market structures, identify white-space opportunities, and calibrate entry or expansion strategies. These details are central to the complete study and are intentionally held back from this preview so that the full report delivers its intended strategic ROI. Readers seeking to benchmark their portfolio, evaluate acquisition targets, or validate regional prioritization will find those answers in the comprehensive dataset.
Turning Intelligence into Advantage in 2026
The 2026 operating environment rewards organizations that can align product strategy with regulatory reality, cost architecture, and demand fragmentation. Tariff volatility and sustainability mandates are no longer isolated risk registers; they are design, sourcing, and pricing constraints that shape what can be built, where it can be sourced, and how it can be positioned. At the same time, consumer demand continues to reward performance, comfort, and credible sustainability, while discretionary spending remains disciplined enough to punish misaligned assortments.
Footwear Market
In this context, the 4.7 percent compound annual growth trajectory through 2032 should be read not as a guarantee of easy expansion, but as a signal that structural demand is intact and that competitive gains will accrue to those who can navigate complexity with precision. Organizations that understand where growth concentrates, how concentration influences pricing and margin behavior, and how compliance and supply chain capacity are evolving will be better positioned to defend share and capture incremental value.
PW Consulting’s Footwear Market study is built for that moment. It offers a rigorous, integrated view of market size, growth pathways, competitive architecture, and the regulatory and consumer dynamics that will define execution in the years ahead. The complete report contains the detailed segmentation splits, regional revenue distributions, and company-level comparative analysis required for direct strategic application.
For executives, category leaders, and investors preparing for 2026 planning cycles, the study provides the foundation to move from awareness to action: prioritize the right segments, anticipate compliance-driven redesign, align sourcing with cost resilience, and position portfolios where demand is most durable. The full intelligence package is available through our research portal, where detailed datasets, methodology notes, and scenario-ready breakdowns can be accessed and integrated into your strategic workflow.
For detailed analysis of this topic, please visit the official page: Footwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Eddy Current Sensor Market to Hit $1.86B by 2032 with 6.5% CAGR
By pmarketresearch, 2026-09-15
Charting Precision: Strategic Intelligence for the Eddy Current Sensor Market in 2026 and Beyond
In an industrial landscape defined by tightening tolerances, automation acceleration, and non-destructive testing mandates, proximity and displacement sensing have quietly become critical infrastructure. Eddy current sensors occupy a unique niche in this ecosystem, offering sub-micron resolution, immunity to dust and oil contamination, and reliable performance in environments where optical or capacitive alternatives falter. As manufacturing footprints fragment across regions and precision requirements escalate, the strategic value of high-fidelity market intelligence cannot be overstated.
This analysis introduces a newly published market research study that maps the trajectory of the global eddy current sensor market from a 2025 base year through a seven-year forecast window extending to 2032. The study is designed not as a static snapshot but as a decision-support instrument for engineering leaders, procurement directors, and corporate strategy teams preparing for the competitive and operational realities of 2026. Below, we outline the strategic architecture of the report, the forces reshaping supply and demand, and the competitive dynamics that will separate market leaders from followers.
From Baseline to 2032: A Revenue Trajectory Built for Scenario Planning
The report anchors its forward-looking assessments in a rigorously back-tested historical series spanning 2020 through 2025, followed by a forecast period that runs from 2026 through 2032. Over the historical window, the market demonstrated consistent expansion, moving from a baseline just above the mid-800-million-dollar range in 2020 to a position approaching 1.2 billion U.S. dollars by 2025. This climb reflects compounding demand drivers: more stringent equipment monitoring in turbomachinery, broader adoption of non-contact measurement on automated production lines, and rising inspection requirements in aerospace, defense, and petrochemical operations.
Looking ahead, the forecast models project a compound annual growth rate of approximately 6.5 percent across the full 2026–2032 horizon. In absolute terms, this translates into a measured but meaningful upward arc: the market is expected to cross the 1.25-billion-dollar threshold in 2026 and continue ascending toward the 1.8-billion-dollar range by 2032. Importantly, these figures are presented in the report as scenario-ready ranges rather than single-point predictions. Decision-makers can stress-test capex plans, production allocations, and inventory strategies against base, upside, and downside cases, adjusting assumptions around cycle times, capital availability, and regional demand timing.
The report deliberately refrains from presenting headline aggregate numbers as the centerpiece. Instead, it uses the macro trajectory to frame a deeper question: where, how, and with whom will the next phase of value creation occur? That framing is what transforms raw sizing data into strategic optionality for 2026 planning cycles.
Inside the Report: Operational Intelligence for Engineering and Commercial Teams
A market study earns its shelf space only when it converts data into action. This report is structured to serve multiple stakeholder functions simultaneously, balancing quantitative rigor with qualitative context. The analytical architecture includes the following core components:
- Segment-Level Demand Architecture. The study disaggregates the market along multiple axes, including product architectures, end-use verticals, and geographic regions. Rather than offering static splits, each segment view is accompanied by demand elasticity commentary, adoption curve positioning, and indicators that signal which sub-segments are likely to outpace or underperform the market average.
- Competitive Benchmarking and Strategic Group Mapping. Company profiles are paired with an assessment of positioning, technology differentiation, and commercial model. The analysis surfaces which players compete primarily on precision and integration, which compete on application-specific inspection configurations, and which are leveraging scale and channel depth to defend share.
- Technology Roadmap and Application Scenarios. The report examines how sensor form factors, measurement ranges, signal-processing capabilities, and environmental ratings are evolving in response to factory automation, turbomachinery monitoring, and NDT inspection requirements. It identifies where engineering trade-offs—accuracy versus robustness, integrated versus split configurations, manual inspection versus automated array-based NDT—are reshaping buyer preferences.
- Supply-Side and Cost Structure Dynamics. Beyond demand, the study traces the upstream factors that influence margin structures and availability. Material inputs, qualification requirements, and trade policy exposure are mapped to the segments and regions they affect most, giving procurement and operations teams early visibility into cost volatility and sourcing constraints.
- Regulatory and Standards Context. Compliance frameworks and personnel qualification standards are analyzed not as abstract policy but as operational determinants that influence inspection throughput, service models, and competitive barriers in specific regions and verticals.
- Scenario and Sensitivity Layers. The report provides a structured basis for exploring how shifts in capital spending, automation adoption, export controls, and commodity prices could alter the pace and geography of growth through 2032.
The practical output is a document that supports product roadmapping, channel strategy, M&A targeting, and client-facing positioning. It is equally useful for a sensor OEM assessing where to invest in next-generation measurement suites, a system integrator evaluating which sensing technologies to specify in automation deployments, and a service provider planning NDT inspection capacity in regulated industries.
Forces Reshaping the Market: Technology, Trade, Materials, and Standards
Market growth at this stage of the cycle is rarely the result of a single driver. In the eddy current sensor space, the forward trajectory is being shaped by a convergence of technical and structural forces that the report examines in detail.
Precision, Durability, and Integration as Competitive Axes
Buyers across factory automation and rotating equipment monitoring are increasingly selecting sensors not only for measurement accuracy, but also for survivability in harsh environments and ease of integration into broader control architectures. Recent product activity underscores this direction. In early 2025, one European specialist introduced a new eddy current displacement sensor series engineered for submicron accuracy combined with IP69K-rated protection, targeting environments where cleaning regimes, humidity, and contamination would compromise less rugged designs. Around the same period, industrial automation players moved to bundle sensing capabilities into broader factory automation ecosystems. A notable example involved a partnership aimed at jointly developing advanced eddy current displacement sensors for high-volume factory automation deployments, with initial targets referencing thousands of installations. In late 2024, a major turbomachinery instrumentation supplier updated specifications for a 5 mm eddy current sensor intended for radial and axial shaft displacement monitoring, reflecting continued emphasis on predictive maintenance and condition monitoring in critical rotating assets.
These developments illustrate a broader shift: sensors are no longer viewed as isolated components but as integrated measurement nodes whose value depends on interoperability, environmental resilience, and the quality of the signal chain behind them.
Non-Destructive Testing as a Structural Demand Engine
NDT remains a foundational application domain for eddy current technology, particularly for crack detection, material sorting, and surface inspection. Demand here is shaped by both regulatory expectations and operational economics. Personnel qualification standards, including ISO 18436-1, require certification for NDT inspectors, reinforcing the value of standardized, repeatable measurement instruments and structured inspection processes. In parallel, the rise of eddy current array probes and advanced NDT instrumentation has expanded inspection coverage and throughput, enabling more efficient defect detection and reducing reliance on labor-intensive point-by-point methods.
The strategic significance of this segment intensified with a major corporate development in early 2026, when a large industrial group completed the acquisition of an eddy current array and NDT specialist. The transaction signals that established industrial portfolios are actively consolidating advanced inspection capabilities, reinforcing the notion that NDT is moving from a peripheral capability to a strategically integrated offering within broader industrial technology and fabrication ecosystems.
Eddy Current Sensor Market
Input Costs, Materials, and Trade Policy as Margin and Availability Variables
On the supply side, margin planning and availability are increasingly-sensitive variables. Copper wire coils used in eddy current probes have faced rising material costs tied to commodity volatility, affecting cost structures across multiple sensor configurations. At the same time, high-frequency sensor designs that depend on magnet assemblies with rare earth materials have encountered export limits originating from China, constraining certain supply chains and prompting reassessment of sourcing strategies. In addition, U.S. tariffs on China-origin sensors have affected supply chain costs for North American manufacturers, adding a trade-policy dimension to regional sourcing decisions.
These dynamics are not merely procurement concerns; they influence where and how products are designed, which specifications become commercially viable at scale, and which customer segments are most exposed to price pressure. The report maps these pressures to the segments and geographies most likely to feel them first, enabling teams to anticipate rather than react.
Competitive Landscape: Strategic Groups and Differentiated Playbooks
The eddy current sensor market is not a monolith. It is a collection of overlapping competitive theaters, each with its own technical priorities, buying committees, and differentiation logic. The report profiles a set of companies that together illustrate the strategic variety in the space and clarify how value is being contested.
Precision Measurement Specialists in Factory Automation and Displacement Sensing
Among the companies shaping the displacement and proximity measurement segment, several are competing on measurement fidelity, robustness, and system-level integration. A German specialist is known for its eddyNCDT series of eddy current displacement sensors, which emphasize high-precision non-contact measurement and have been extended into newer series engineered for demanding industrial conditions. In the United States, another specialist has built its reputation around ECL-series eddy current linear encoders and displacement sensors, positioning close to factory automation and precision motion control applications. A Japanese measurement systems company integrates eddy current displacement sensors into broader measurement platforms, leveraging system-level reach and a wide customer base to scale adoption.
For these players, strategic advantage is often built on control over the measurement chain—signal stability, environmental resilience, calibration consistency, and the ability to integrate cleanly with controllers, HMIs, and automation architectures. Competition here tends to reward incremental precision gains, ruggedization, and application-specific tuning.
NDT-Focused Players and the Inspection Technology Tier
A second strategic group is oriented more directly around inspection and non-destructive testing. A Canadian company has gained recognition for eddy current array probes and instruments designed for NDT inspections, where coverage, scan efficiency, and data interpretation are central value drivers. A German test instrument manufacturer focuses on eddy current test instruments and probes for crack detection and material sorting, emphasizing reliability in inspection workflows. A Chinese supplier has expanded its presence in eddy current detectors and testing systems for NDT applications, reflecting broader momentum in cost-sensitive inspection markets and regional industrial growth.
In this tier, differentiation frequently comes from probe geometry, array coverage, portability, software-enabled interpretation, and the ability to meet application-specific inspection standards. The 2026 acquisition of a leading NDT-focused eddy current array company by a larger industrial corporation illustrates how this part of the market is attracting strategic consolidation from buyers seeking to embed advanced inspection capability into broader industrial offerings.
Turbomachinery, Vibration, and Asset Monitoring Specialists
A third group competes closer to rotating equipment and asset condition monitoring, where displacement, vibration, and proximity measurement support predictive maintenance and machinery protection. A major industrial instrumentation company has extended its portfolio with eddy current sensors such as the AMS EZ 1000 series, aimed at turbomachinery radial and axial displacement and vibration monitoring. A U.S.-based precision instruments company offers eddy current proximity probes for displacement and vibration measurement, serving customers who depend on continuous machinery health data in critical installations.
Here the buying center often spans reliability engineering, maintenance operations, and instrumentation procurement, and the value proposition ties directly to uptime, alarm accuracy, and integration with asset management systems. The competitive bar is shaped by long service life, proven reliability in harsh rotating equipment environments, and the ability to support standardized maintenance processes.
Taken together, these profiles show that the market is being contested on multiple fronts simultaneously. Some companies are winning through precision and integration; others through inspection-domain specialization; others through sector-specific reliability and channel reach. The report’s competitive analysis is designed to help organizations identify which strategic group their offerings align with, where substitution risk is highest, and which competitor moves should be monitored most closely in 2026.
Eddy Current NDT Equipment Market
Geographic and Segment Signals Without Data Overload
The report’s geographic and application segmentation is presented not as a wall of percentages, but as a set of directional signals that inform where growth is concentrating and where competitive intensity is likely to rise. Regionally, the analysis examines how mature industrial automation markets compare with faster-growing inspection and manufacturing regions, and how trade policy, sourcing exposure, and standards environments alter the growth calculus in each geography. It also addresses how different regions are positioned relative to key applications, from factory automation and displacement measurement to aerospace, defense, power generation, and petrochemical inspection.
On the application side, the report traces where demand is being reinforced by structural factors—such as rotating equipment monitoring in power generation and turbomachinery, inspection mandates in aerospace and defense, and process-related monitoring in petrochemical operations—versus where growth is more cyclical or discretionary. By separating structurally supported demand from more volatile demand pockets, the study helps leaders prioritize investments and allocate commercial resources more deliberately.
This approach avoids the trap of treating segmentation as a formatting exercise. Instead, it uses segment context to answer strategic questions: which applications are likely to sustain multi-year sensor spending, which customer groups face the stiffest cost or qualification pressures, and which geographic markets present the most attractive combinations of demand growth and manageable risk.
Concentration, Barriers, and Where Competitive Advantage Is Being Built
Market structure matters because it reveals how difficult it is to enter, scale, and defend share. The report notes a moderately concentrated competitive environment, with the top three participants holding a meaningful combined share and the top five extending that position further. Such concentration typically reflects accumulated advantages in measurement performance, application expertise, qualification credibility, distribution reach, and long-term customer relationships in demanding industrial settings.
At the same time, concentration is not uniform across all segments. In some application areas, specialization and inspection-specific know-how can create effective local leadership even where overall market share is modest. In others, integration capability and channel scale can compensate for narrower technical specialization. The report maps these dynamics so that companies can see not just who leads today, but what kinds of capabilities are likely to determine leadership tomorrow.
For incumbents, the strategic imperative is to reinforce the attributes that make substitution costly: proven accuracy under real operating conditions, robust environmental ratings, reliable calibration and service support, and integration paths that reduce total cost of ownership. For challengers and new entrants, the opportunity often lies in targeted segments where a specific technical advantage, lower-cost architecture, or software-enabled workflow can convert into a defensible position before scale competitors respond.
How to Use This Intelligence for 2026 Decision-Making
The report is designed to be used, not merely read. In practice, it can support several high-priority 2026 decisions:
- Product and engineering roadmapping. Teams can align sensor development investments with the configurations, environmental ratings, and application requirements most likely to drive differentiated demand, rather than reacting to generalized market narratives.
- Commercial and channel strategy. Sales leaders can prioritize geographies and application segments where demand momentum and competitive positioning are most favorable, and adjust messaging to match the procurement and engineering priorities of each buying center.
- Procurement and supply resilience. Operations and sourcing teams can anticipate where material volatility, rare earth exposure, and trade-policy friction are most likely to affect cost and availability, and can diversify or reconfigure supply accordingly.
- M&A and partnership evaluation. Corporate development teams can use the competitive and technology mapping to identify capability gaps, acquisition targets, and partnership opportunities, especially in NDT, automation integration, and turbomachinery instrumentation.
- Investment and scenario planning. Finance and strategy teams can use the forecast architecture to test capital allocation decisions against multiple growth paths, ensuring that commitments are robust to variation in demand timing and regional performance.
The underlying message is consistent: the most valuable insights are not the headline numbers alone, but the structured reasoning behind them and the operational implications they imply. A 6.5 percent growth trajectory, for example, becomes actionable only when it is linked to which applications are expanding fastest, which product types are gaining share, and which supply-side constraints might shape margin outcomes.
Why the Full Study Matters and How to Access It
This article has outlined the strategic logic, competitive architecture, and demand-supply forces that define the eddy current sensor market heading into 2026. It has also indicated why the complete study is more than a data set: it is a decision framework that connects market sizing, segmentation context, competitive profiling, recent product and corporate developments, and structural risk factors into a coherent basis for planning.
To support rigorous decision-making, the full report goes further. It provides detailed segment-level breakdowns, company-specific positioning assessments, application-by-application demand commentary, regional growth context, and scenario-ready forecast structures. It also examines how recent product launches, partnerships, specification updates, and acquisitions are reshaping competitive expectations in real time.
For strategy, engineering, procurement, and commercial leaders who need to move beyond directional market narratives and into specific allocation, sourcing, and positioning choices, the complete study is the appropriate reference point. The full intelligence package, including segment splits, regional and application detail, and the complete competitive set, is available through the official report page. We invite interested teams to review the full publication and use it as a foundation for 2026 strategy development.
For detailed analysis of this topic, please visit the official page: Eddy Current Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IC Substrate Market Hits $10B in 2025, Projected 6.63% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Horizons in the IC Substrate Market: A 2026 Executive Brief
The integrated circuit (IC) substrate market stands at a critical inflection point as 2026 unfolds. Driven by the insatiable demand for artificial intelligence (AI) computational power, the proliferation of high-performance computing (HPC), and the electrification of automotive platforms, the industry is experiencing a structural shift in both volume and value. For executive leadership and strategic planners, understanding the trajectory of this market is not merely an academic exercise but a prerequisite for capital allocation, supply chain resilience, and long-term competitive positioning.
PW Consulting's latest market research report, "IC-Substrate Market 2026-2032," offers a comprehensive analytical framework designed to navigate this complex landscape. This article serves as a strategic preview of the report's findings, highlighting the macro-economic trends, competitive dynamics, and operational imperatives that will define the industry over the next seven years. While we outline the broad strokes of the market evolution here, the full intelligence required for precise decision-making lies within the detailed data tables, segment-specific forecasts, and proprietary competitive matrices available in the complete study.
Market Trajectory and Growth Dynamics
The historical resilience of the IC substrate sector provides a strong foundation for future growth projections. Drawing on historical data spanning 2020 through 2025, the market has demonstrated a consistent upward trajectory despite global supply chain disruptions and geopolitical headwinds. The consolidated revenue figures for the recent past reflect steady expansion, culminating in a base year valuation for 2025 that underscores the sector's maturity and integral role in the electronics ecosystem.
Looking forward, the forecast period from 2026 to 2032 indicates a sustained growth momentum. The analysis projects a compound annual growth rate (CAGR) of 6.63 percent USD over this horizon. This growth is not uniform; it is heavily skewed by technological advancements and specific application drivers. The market size is expected to expand significantly by the end of the forecast period, reaching new valuation highs in 2032. Such growth rates suggest that IC substrates will remain a critical bottleneck and opportunity zone for downstream electronics manufacturers.
Technology Segments and Application Drivers
The market is segmented by technology type and end-use application, each presenting distinct risk and reward profiles. In terms of substrate types, the landscape is dominated by advanced packaging solutions required for high-density interconnects. Key categories include Flip-Chip Ball Grid Array (FC-BGA), Flip-Chip Chip Scale Package (FC-CSP), and other specialized substrate types. The shift toward higher performance computing necessitates substrates that can handle greater power densities and signal speeds, favoring advanced variants within these categories.
On the application side, the demand signal is led by the Mobile and Consumer electronics sector, which continues to drive volume. However, the quality and value growth is increasingly derived from the Automotive and Transportation sector, as well as the IT and Telecom industry. The emergence of AI servers, autonomous driving systems, and advanced telecommunications infrastructure is reshaping the demand mix, placing premium substrates at the center of supply chain strategy. Our report dissects these segments to reveal where margin expansion is most viable, though specific volume splits and regional contributions are detailed exclusively in the full dataset to maintain competitive confidentiality.
Competitive Landscape and Strategic Consolidation
The IC substrate market is characterized by a moderate to high level of concentration, with top players commanding a significant share of global revenue. Our analysis indicates a CR3 of approximately 54 percent and a CR5 of 60 percent, highlighting the dominance of entrenched incumbents who possess the technical capability and capital depth to invest in next-generation manufacturing. This concentration suggests that barriers to entry remain high, particularly for technologies involving Advanced Build-up Film (ABF) and glass-core substrates.
Several key companies define the current competitive arena. Firms such as Ibiden Co., Ltd., Unimicron Technology Corp., and AT&S Austria Technologie & Systemtechnik AG are at the forefront of innovation, particularly in high-performance applications. These players are not merely competing on price but are engaging in a race for technological superiority and capacity leadership. Regional players in Japan, Taiwan, South Korea, and Austria are expanding their footprints, often supported by government incentives aimed at securing semiconductor supply chains.
Samsung Electro-Mechanics and LG Innotek represent significant competitive forces from South Korea, leveraging vertical integration and strong domestic demand. Meanwhile, companies like Kinsus Interconnect Technology Corp., Shinko Electric Industries Co., Ltd., and Nan Ya PCB Corporation are positioning themselves to capture specific niches within the AI and server packaging value chain. Kyocera Corporation also remains a notable entity, focusing on specialized laminate technologies. The interplay between these entities involves capacity expansions, pricing strategies, and technological partnerships that our report analyzes in depth.
Operational Dynamics: Capacity, Materials, and Regulation
The operational environment for IC substrate manufacturers in 2026 is defined by a tension between surging demand and supply chain constraints. A primary theme in our research is the massive capital expenditure programs undertaken by leading firms. For instance, recent announcements highlight capital investments exceeding hundreds of billions of yen and trillion-won ranges dedicated to expanding high-performance IC package substrate capacity. These investments are targeted specifically at plants capable of serving AI server demands, with mass production timelines ramping up from fiscal 2027 onwards.
Technology advancement is another critical vector. The industry is moving beyond traditional organic substrates toward glass-core and multifunctional core technologies. Recent developments indicate that some leaders have advanced glass-core substrate technology from R&D to industrial deployment, targeting AI, HPC, and even photonics applications. This technological leap is essential for overcoming signal loss and thermal challenges in next-generation packages.
However, capacity expansion is complicated by raw material volatilities. The market faces persistent shortages in critical inputs such as fiberglass and base resins. Supply chain intelligence indicates that key material suppliers have adjusted pricing significantly, with some substrate film prices increasing by over 30 percent due to base resin supply constraints. This inflationary pressure on raw materials is forcing manufacturers to reconsider pricing strategies. In response, leading substrate providers have begun raising prices for premium ABF substrates to offset costs and manage capacity constraints, signaling a shift in the cost structure for downstream customers.
Regulatory support remains a potent accelerant for market growth in key regions. Government initiatives aimed at bolstering domestic semiconductor manufacturing are providing substantial financial backing. For example, funding mechanisms totaling hundreds of millions of USD have enabled specific capacity projects in North America, targeting significant panel production volumes by late 2027. Similarly, European initiatives have awarded substantial grants for plant expansions in Austria, adding tens of thousands of FC-BGA panels to monthly production capacity starting in 2027. These geopolitical interventions are reshaping the global supply map, reducing reliance on single-region sourcing and encouraging localized production hubs.
Strategic Imperatives for 2026 Decision Makers
For industry participants, the insights contained in this study translate into several actionable strategic imperatives. First, supply chain diversification is no longer optional. With material shortages and geopolitical risks influencing the flow of critical substrates, organizations must develop multi-source strategies. Second, technology roadmapping must align with the shift toward glass-core and high-density interconnect solutions to avoid obsolescence in AI and HPC segments.
Third, capacity planning requires a nuanced understanding of lead times and allocation risks. As key players prioritize high-margin AI server contracts, availability for other segments may become constrained, necessitating earlier locking-in of volumes. Finally, pricing negotiations must account for the structural increase in raw material costs and the premium nature of advanced substrate technologies.
The detailed segmentation data, company profiles, and granular forecast models within our full report provide the specific intelligence needed to validate these strategies. Access to the complete analysis allows clients to benchmark their internal projections against market-wide data, identify underserved niches, and anticipate the moves of key competitors with greater precision.
Conclusion
The IC-Substrate Market from 2026 to 2032 presents a landscape of robust growth tempered by complex operational challenges. The convergence of AI demand, technological innovation in substrate materials, and strategic government intervention creates a dynamic environment where informed decision-making is a key differentiator. The macro trends point to a market expanding significantly in value, driven by high-performance applications that demand superior interconnect solutions.
IC Substrate Market
PW Consulting's comprehensive study offers the depth and breadth required to navigate this terrain. By leveraging the detailed forecasts, competitive profiles, and risk assessments outlined in the full report, stakeholders can secure a decisive advantage in procurement, investment, and strategic planning. We invite industry leaders to access the complete research document to unlock the full spectrum of data and insights necessary for thriving in this evolving market.
IC-Substrate Market
For detailed analysis of this topic, please visit the official page: IC-Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rotary Indexer Market Hits $2.07B in 2025, Projects 5.49% CAGR Through 2032
By pmarketresearch, 2026-09-15
Rotary Indexer Market: Strategic Intelligence for 2026 Decision-Makers
The landscape of industrial automation is shifting beneath the feet of even the most seasoned operators. As factories strive for higher throughput, tighter tolerances, and greater flexibility, the rotary indexer has cemented its role as a backbone component in modern production lines. Yet, knowing the market exists is vastly different from understanding where the value pools are forming, which technologies are gaining dominance, and how regulatory headwinds will reshape supply chains in the coming years. The Rotary Indexer Market research released by PW Consulting is designed to bridge that gap, offering a granular, data-driven perspective tailored for executive decision-making in 2026 and beyond.
This article serves as a strategic preview of the full study. It outlines the macro trajectory of the sector, highlights the practical deliverables contained within the report, and examines the competitive and regulatory forces that will define the market rhythm. The goal is not to merely present numbers, but to provide a framework for evaluating investment, procurement, and partnership strategies in a sector poised for steady, meaningful expansion.
Market Trajectory and Growth Dynamics
The global market for rotary indexers has demonstrated resilience and consistent expansion over the past half-decade. Historical analysis from 2020 through 2025 reveals a clear upward arc, with revenue climbing from approximately 1,472 million USD to a projected 2,070 million USD in the base year. This growth reflects the broader industrial push toward modularity, precision assembly, and the integration of automated motion control into both legacy and greenfield facilities.
Looking forward, the forecast period spanning 2026 to 2032 signals continued momentum. Market revenue is anticipated to reach 2,226 million USD in 2026, with a steady compound annual growth rate of 5.49 percent carrying the sector toward 3,005 million USD by the close of the forecast window in 2032. This trajectory is not merely a linear extrapolation; it is underpinned by structural shifts in manufacturing footprints, the electrification of motion systems, and the growing demand for high-cyclical indexing solutions in sectors ranging from consumer goods to precision electronics.
For strategy leaders, this macro view offers a critical anchor: the market is not experiencing a speculative boom, but a measured, industrially grounded expansion. The 5.49 percent CAGR suggests that growth will be distributed across multiple drivers rather than concentrated in a single wave. Understanding which operational segments, configurations, and end-use industries are capturing disproportionate share of this growth requires the kind of segmentation depth that only the full report can provide. We deliberately leave those granular splits and comparative percentages for the detailed analysis, encouraging readers to explore the source material for the precise breakdowns that will inform their specific verticals.
What the Report Delivers: Actionable Frameworks for Strategy
PW Consulting's study is structured to move beyond high-level trend spotting and into the operational specifics that matter to pricing, sourcing, technology roadmapping, and competitive positioning. The research integrates quantitative modeling with qualitative industry intelligence to create a multi-dimensional view of the rotary indexer ecosystem. Decision-makers will find these core components particularly valuable:
- Historical and forecast market sizing anchored in transparent methodology, enabling reliable scenario planning and capacity forecasting.
- Detailed technology and application cross-analysis that maps how different indexing architectures perform across distinct manufacturing workflows.
- Supplier landscape evaluation that distinguishes between product specialization, regional strengths, and integration capabilities.
- Regulatory and compliance mapping across major markets, highlighting certification pathways and safety requirements that influence time-to-market and total cost of ownership.
- Supply chain sensitivity analysis that identifies exposure points related to component availability, trade friction, and logistics volatility.
- Strategic recommendations tailored to different roles, including OEM engineering teams, automation integrators, and procurement leaders evaluating vendor consolidation.
Each section of the report is built to answer the practical questions that arise when a company is deciding whether to standardize on a particular indexing technology, expand into a new geographic market, or restructure supplier relationships. Rather than presenting a static snapshot, the study is designed to serve as a living reference point for quarterly reviews, capex justification, and long-range operational planning.
Competitive Landscape: A Fragmented Field with Clear Differentiators
The rotary indexer market remains moderately concentrated, with the top three players accounting for 24.6 percent of revenue and the top five reaching 26.2 percent. This concentration level indicates that while established manufacturers hold meaningful share, there is ample room for specialized firms, regional players, and innovators to compete on performance, customization, and service ecosystems. Competition in this space is increasingly defined not by price alone, but by the ability to deliver precision, cycle consistency, integration readiness, and compliance assurance.
Worldwide Fixed Rotary Index Tables Market
Several companies illustrate the divergent strategies shaping the market. Motion Index Drives, based in Troy, Michigan, has built its reputation on cam-driven rotary indexing tables and custom solutions aimed at high-cycle automation in aerospace, automotive, and packaging environments. Their focus on engineered applications underscores a segment of the market where bespoke design and durability take precedence over standardized off-the-shelf units.
Rotary Indexer Market
Nexen Group, headquartered in Providence, Rhode Island, approaches the market through high-torque and moment-load capacity, offering servo and ring-drive rotary indexers tailored for precision industrial positioning. Their product philosophy aligns with applications where load dynamics and positional accuracy are critical, particularly in heavier or more demanding manipulation tasks.
WEISS GmbH, operating from Buchen, Germany, produces both programmable and fixed-station rotary indexing tables with digital controls and integration capabilities. Their footprint spans automotive, medical, and electronics assembly, and their recent activity highlights the pace of strategic maneuvering in the sector. In September 2025, WEISS showcased linear workpiece transport and rotary indexing solutions at Automatica 2025, reinforcing their visibility in high-profile automation forums. Earlier that year, in July 2025, the company entered a strategic technology partnership with Shanghai YiNGUAN Semiconductor Technology Co., Ltd. to advance precision automation solutions. These moves illustrate how established European manufacturers are deepening partnerships and channel presence to serve electronics and semiconductor workflows with greater localization and technical alignment.
Destaco, based in Wixom, Michigan, develops mechanical and servo rotary indexers, roller dials, and drives for assembly and packaging equipment. Their breadth of mechanical and electromechanical offerings positions them as a flexible partner for integrators who need to match indexing solutions to varied line architectures. Centricity Automation, also based in the United States, produces EZ and MS series servo rotary indexers designed for PLC-integrated and independent high-precision assembly applications, emphasizing control compatibility and repeatability.
On the Asia-side, Sanko Automation manufactures hollow and fixed-station rotary indexing tables with programmable controls for factory automation, addressing demand for compact, integration-friendly designs. TallMan Robotics, also based in China, designs shaft-output rotary indexers and cam index drives for engineered automation motion, reflecting the broader push by regional manufacturers to offer engineered motion solutions that can be tailored to specific line configurations. Taktomat GmbH, headquartered in Germany, supplies rotary indexers with fixed and flexible division for high-speed production lines, appealing to operations that prioritize throughput consistency and adjustable station division.
Festo, another Germany-based player, offers pneumatic DHTG series rotary indexing tables for partially automated and buffer systems. Their presence in the pneumatic segment highlights an important strategic reality: not every application demands servo-level precision, and pneumatic indexing remains relevant for buffer handling, partial automation, and cost-sensitive lines where speed and simplicity outweigh high-torque requirements.
Together, these companies demonstrate that leadership in the rotary indexer market is multifaceted. Some firms compete on custom engineering and high-cycle durability, others on servo precision and integration, and still others on pneumatic efficiency or regional scale. The full report dissects these competitive positions in greater detail, mapping product strategies, market emphasis, and the operational implications for buyers evaluating long-term vendor relationships.
Industry Dynamics: Regulation, Supply Chain, and the Compliance Premium
Market growth does not occur in a vacuum. The rotary indexer sector is being shaped by a set of cross-cutting dynamics that influence design choices, deployment timelines, and regional expansion strategies. Regulatory compliance, in particular, has moved from a backend checkbox to a frontline strategic consideration.
In North America, machinery incorporating rotary indexers must comply with OSHA standards under 29 CFR 1910 Subpart O. For electrical safety and reliability in North American installations, UL certification is required, and failure to meet these expectations can delay project approvals and complicate integration with broader facility safety systems. In Europe, the EU Machinery Directive 2006/42/EC applies, with CE marking required for market access. These frameworks create a compliance premium for manufacturers and integrators who must embed safety, documentation, and verification into their product and deployment processes.
In China, rotary indexers require GB/T 5226.1 machinery safety certification for industrial use, while in India, IS/ISO 12100 standards govern safety expectations for industrial equipment. For companies operating across multiple jurisdictions, the cumulative weight of these certification requirements can affect product versioning, testing cycles, and time-to-deployment. The report examines how these regulatory layers interact with procurement timing, vendor selection, and the total cost of compliance for different installation profiles.
Supply chain conditions represent another critical dynamic. Disruptions stemming from geopolitical tensions and trade restrictions continue to act as a major restraint on rotary indexer production schedules. Component availability, logistics bottlenecks, and tariff exposure can alter not only unit economics but also the reliability of delivery commitments. For operations that depend on synchronized line builds or phased automation rollouts, supply chain volatility can introduce hidden schedule risk that is often more costly than the headline price differences between suppliers. The study incorporates these dynamics into its market outlook, helping leaders anticipate where procurement flexibility, dual-sourcing strategies, and regional inventory planning may become necessary.
These forces also influence technology adoption. As compliance requirements become more stringent and supply chains less predictable, buyers are increasingly favoring solutions that offer robust documentation, reproducible safety integration, and modular replaceability. That preference is gradually favoring suppliers who invest in certified product platforms, clear integration guidance, and support ecosystems that reduce deployment friction. The full market research explores how these dynamics play out across different configurations and end-use industries, providing the kind of operational context that pure market sizing cannot capture.
Implications for 2026 Strategic Planning
For executives planning around 2026, the rotary indexer market offers a case study in balanced opportunity. The macro forecast points to durable growth, but the real strategic value lies in understanding which levers will matter most for a given organization. A packaging equipment manufacturer may prioritize configuration trends and application fit. An automation integrator may focus on supplier integration capabilities and compliance readiness. A procurement leader may need to weigh regional supply risk against total cost of ownership, factoring in certification pathways and lead-time reliability.
The report is designed to support these varied perspectives without flattening them into a single generic narrative. It maps market size evolution, segmentation patterns, competitive positioning, and external dynamics into a coherent decision-support structure. Readers who engage with the full study gain access to the detailed splits and comparative analysis that make it possible to move from directional confidence to precise action.
The 5.49 percent CAGR and the projected rise to 3,005 million USD by 2032 tell a story of sustained demand, but the strategic question for 2026 is not simply whether the market is growing. It is where growth is concentrating, which technologies are gaining relative advantage, how compliance and supply conditions are reshaping vendor selection, and which competitors are positioning themselves to capture premium segments in electronics, automotive, food and beverage, and assembly-intensive operations. Those answers require the full intelligence package.
Conclusion: Building Confidence Through Depth
PW Consulting's Rotary Indexer Market research is intended to provide more than an overview; it is built to serve as a strategic reference for organizations making real investment, sourcing, and technology decisions in a market that rewards precision, reliability, and forward-looking planning. The preview above has highlighted the growth trajectory, the competitive diversity, and the regulatory and supply chain dynamics that define the operating environment. It has intentionally left the detailed segmentation data, application splits, and regional comparisons for the complete report, because the true value of the study lies in that depth.
For leaders who need to validate assumptions, structure procurement strategies, assess vendor portfolios, or plan for multi-year automation roadmaps, the full report offers the granularity required to act with confidence. As the market moves through its forecast arc toward 2032, the organizations that succeed will be those that combine macro awareness with detailed, actionable intelligence. This research is designed to provide exactly that foundation.
For detailed analysis of this topic, please visit the official page: Rotary Indexer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com